Accounting practice financial model, built free.
A three-statement Excel model for an accounting and tax practice, built from your own figures and checked to balance.
- Free account
- No card
- Usually ready within the hour
We use generative AI in parts of our process, so mistakes can occur. Every model should be checked by a person before it is relied on. Read more
Accounting, tax, bookkeeping, audit and advisory practice with a base of recurring compliance clients billed annually or monthly, a busy season around tax deadlines, and partners paid from profits; practices trade at a multiple of recurring fees.
In short
- 01
Three linked statements
Income statement, balance sheet and cash flow, linked in every period.
- 02
Valued two ways
Discounted cash flow and trading multiples, side by side.
- 03
Monthly to annual
Monthly, quarterly, half-yearly or annual periods, for up to 30 years.
- 04
Checked every period
A Checks sheet shows the balance sheet balances and the cash reconciles.
The sample, as Excel draws it.
Built by the same system and checks as yours, on illustrative figures: every sheet as Excel draws it, or live.
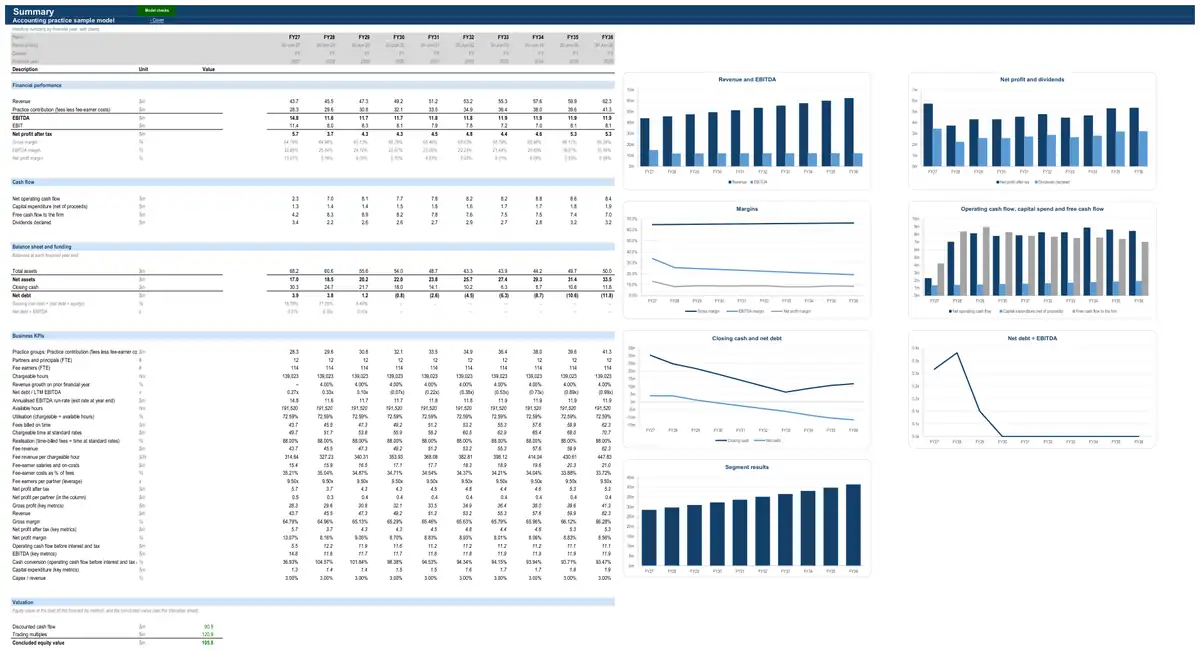
Illustrative figures: the sample describes no real business. The live preview shows values; your model’s Excel file has every formula.
How the model works for an accounting practice.
- How it earns revenue3 formulasFee revenue and realisation · All practice groupsTotal weightPartnersDirectorsManagersSeniorsGraduatesFee revenue and realisation · All practice groupsFee revenueChargeable time at standard ratesTime written off (below standard rates)Fee revenue and realisation · All practice groupsChargeable time at standard ratesChargeable hoursfrom chargeable hours and utilisationBlended standard charge-out rate
- What drives its costs3 formulasFee-earner headcount and staff cost · All practice groupsFee-earner salaries and on-costsAnnual salary bill at current ratesOn-costs (superannuation, payroll tax, leave)share of the yearFee-earner headcount and staff cost · All practice groupsDirectors and senior managersPartners and principalsDirectors per partnerFee-earner headcount and staff cost · All practice groupsManagersPartners and principalsManagers per partner
- What it invests in3 formulasCorporate fixed assetsCapital expenditureRevenuefrom statementsCapex as % of revenueAdditional planned capexCorporate fixed assetsDepreciationDepreciation of the opening asset baseDepreciation of new capexCorporate fixed assetsClosing net book valueOpening net book valueCapital expenditureDepreciation
- How it is funded3 formulasDebtRepaymentsScheduled repaymentsPrepayments from an equity raise and the cash sweepDebtClosing balanceOpening balanceDrawdownsRepaymentsDebtInterest expenseOpening balanceAll-in interest rateshare of the year
- How profit becomes cash3 formulasWork in progress (unbilled) · All practice groupsWork in progress (unbilled fees)Fee revenuefrom fee revenue and realisationWIP daysDays in period (on a 365-day year)Work in progress (unbilled) · All practice groupsFee debtors (billed and unpaid)Fee revenuefrom fee revenue and realisationDebtor daysDays in period (on a 365-day year)Working capitalTrade receivablesRevenuefrom statementsDebtor daysDays in period
19 parts, each one tested.
Every part is a tested building block with its own checks: yours is put together from the ones your business needs.
- CPI forecastConsensus curve with long-run anchor
- Operating expensesHeadcount build by function
- Corporate costsFixed cost base indexed to CPI
- Working capitalFull working capital
- Income taxCorporate rate with tax losses
- Corporate fixed assetsStraight-line over remaining life
- DebtAmortising term loan
- Dividends and distributionsPayout of net profit
- Discounted cash flow valuationDCF on free cash flow to the firm
- Multiples valuationEV / EBITDA multiple
- Partner remuneration and profit shareSalaried partners and bonus poolThe cost (or profit share) of partners and principals, and profit per equity partner.
- LeasesLease register
- Key-metric summaryLast-twelve-month and run-rate metrics
- Discount rate (WACC)CAPM at target gearing
- Terminal valuePerpetuity growth on normalised cash flow
- Fee-earner headcount and staff costLeverage pyramidFee earners by grade (the headcount pyramid) and their salary cost.
- Chargeable hours and utilisationUtilisation by gradeChargeable hours from available hours × utilisation.
- Fee revenue and realisationHours × rate × realisationFees earned by a practice, after realisation (the share of standard value actually billed and collected).
- Work in progress (unbilled)Lock-up target split into WIP and debtorsUnbilled work in progress; together with debtors from working capital it forms lock-up.
The numbers it tracks.
- 01recurring fee base
- 02fees per client
- 03client retention
- 04chargeable hours
- 05WIP days
- 06profit per partner
More in professional services.
- Professional services firm financial model
- Law firm financial model
- Consulting firm financial model
- Engineering consultancy financial model
- Architecture practice financial model
- Translation services financial model
Looking for an accounting practice financial model template? Ours arrives built for your business, with your figures in it.
Running a small business? Read what goes into a small business financial model.
See a finished model, sheet by sheetThe sample is built on illustrative figures and describes no real business. Models are calculations prepared from the information you provide. They are not financial advice and must be independently verified. See our terms.