Salt producer financial model, built free.
A three-statement Excel model for a salt producer, built from your own figures and checked to balance.
- Free account
- No card
- Usually ready within the hour
We use generative AI in parts of our process, so mistakes can occur. Every model should be checked by a person before it is relied on. Read more
Produces solar salt by evaporating seawater or brine in ponds and harvesting it, or mines rock salt, selling it for chemical manufacture, de-icing and food under contracts.
In short
- 01
Three linked statements
Income statement, balance sheet and cash flow, linked in every period.
- 02
Valued two ways
Discounted cash flow and trading multiples, side by side.
- 03
Monthly to annual
Monthly, quarterly, half-yearly or annual periods, for up to 30 years.
- 04
Checked every period
A Checks sheet shows the balance sheet balances and the cash reconciles.
The sample, as Excel draws it.
Built by the same system and checks as yours: its structure and its inputs, ready for your own figures.
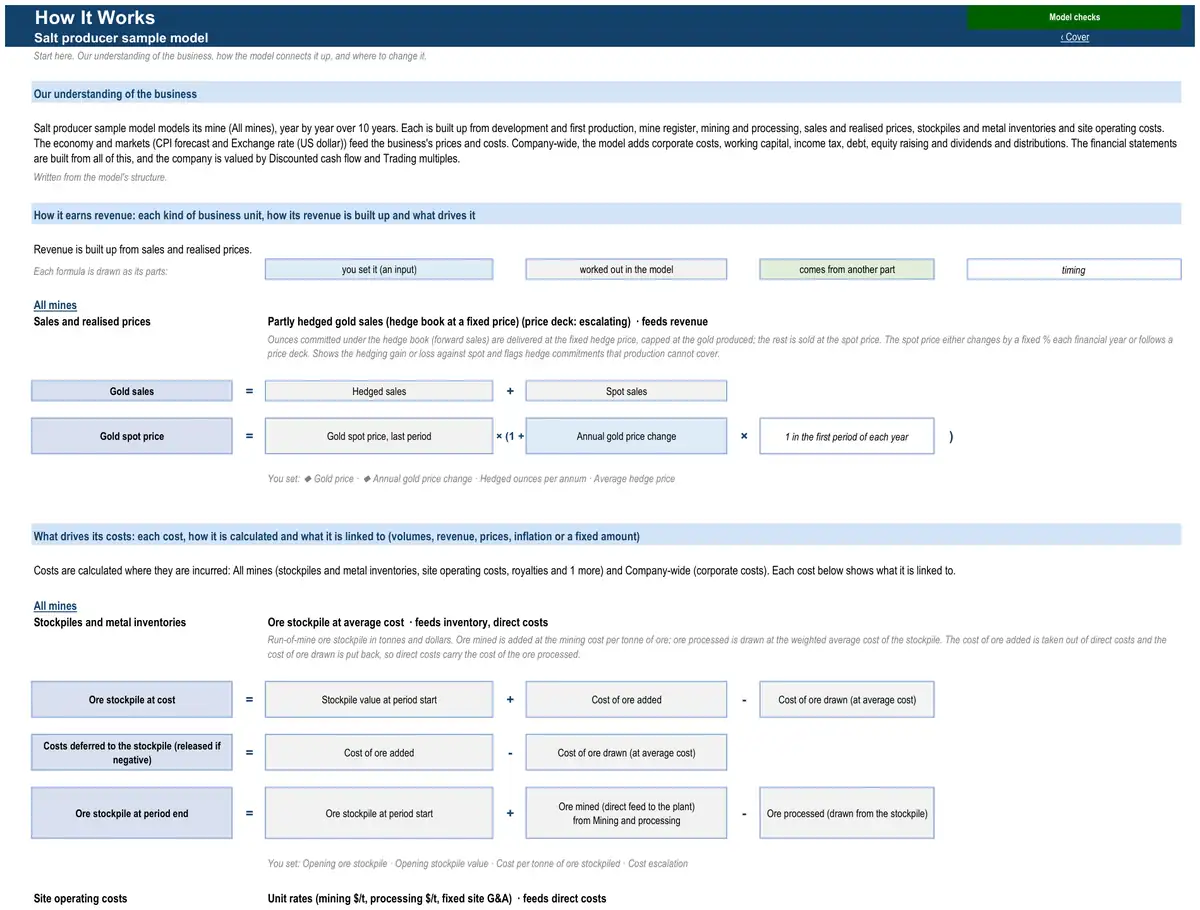
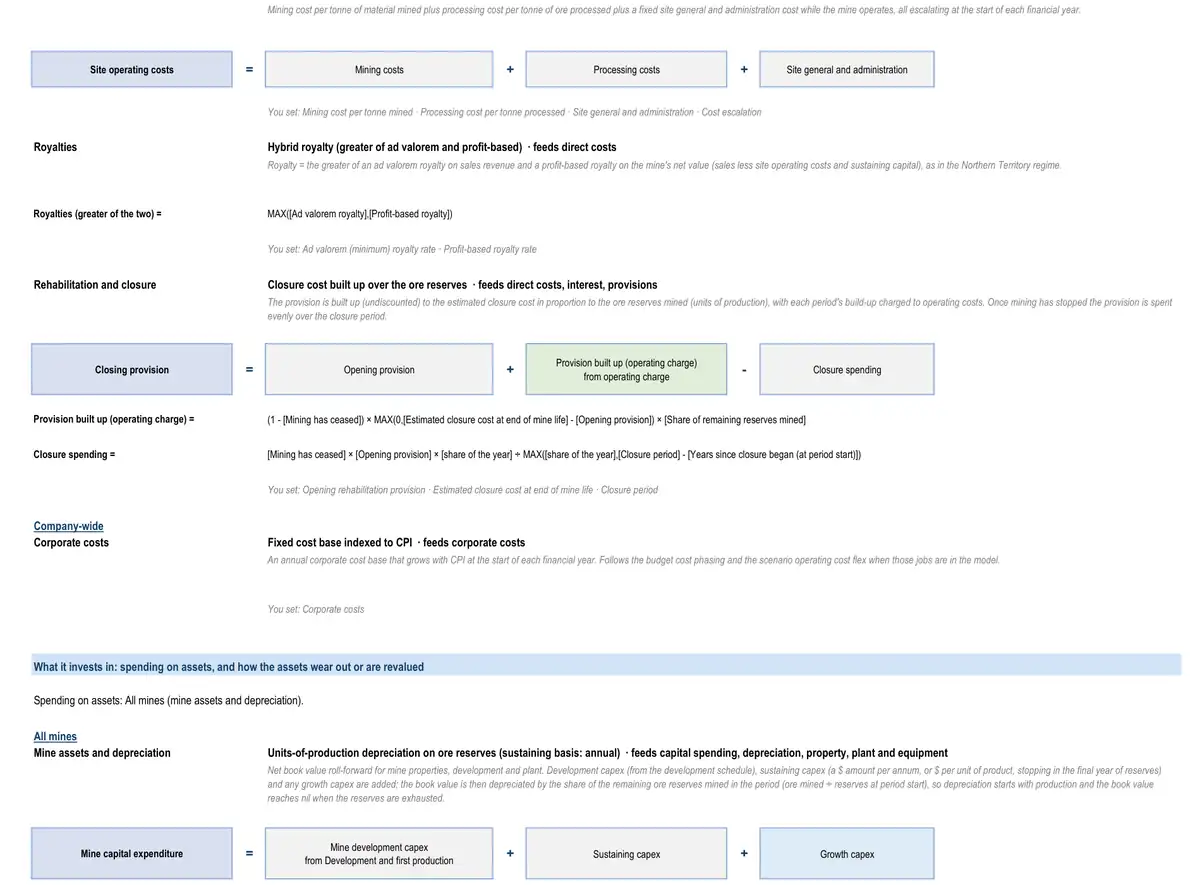
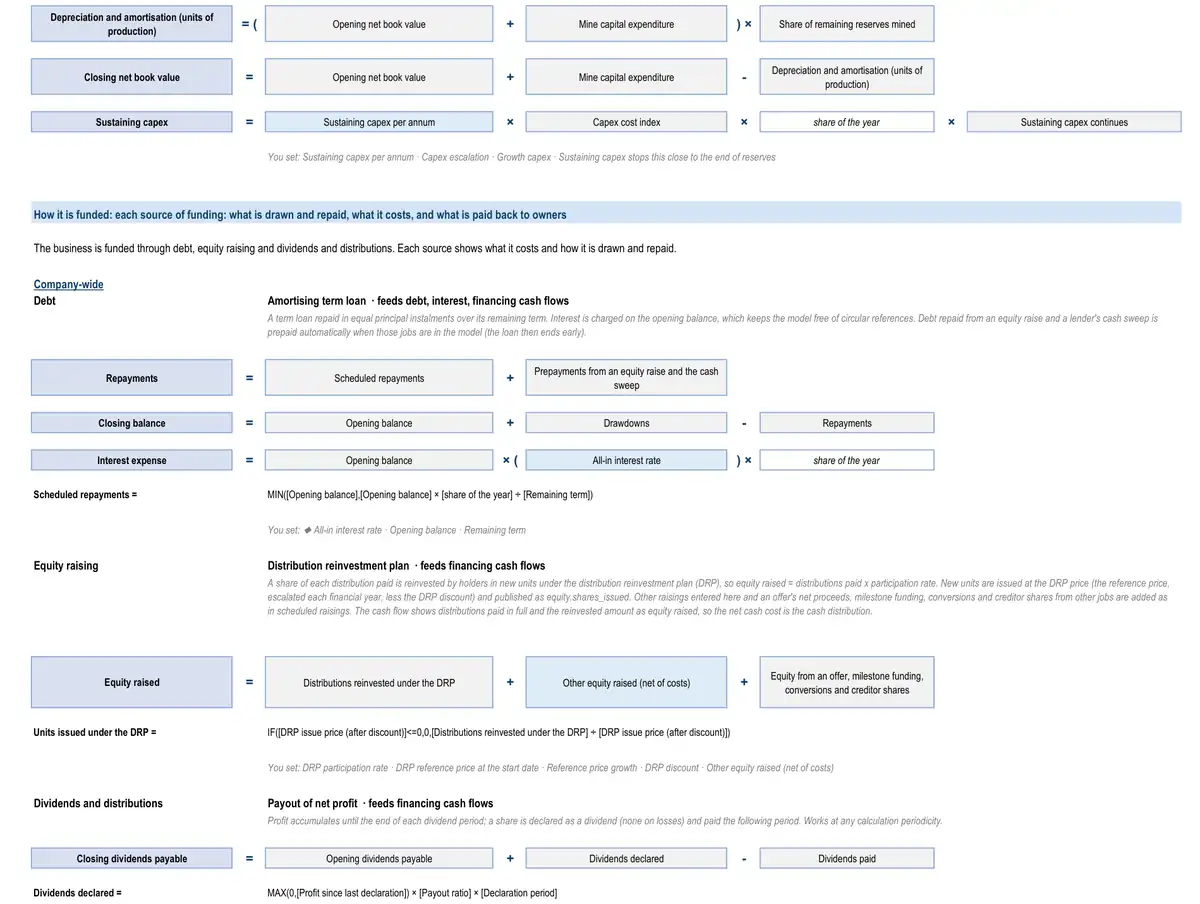
The sample describes no real business. Yours is calibrated to your own figures, so its results are your business’s.
How the model works for a salt producer.
- How it earns revenue2 formulasSales and realised prices · All minesGold salesHedged salesSpot salesSales and realised prices · All minesGold spot priceGold spot price, last periodAnnual gold price change1 in the first period of each year
- What drives its costs3 formulasStockpiles and metal inventories · All minesOre stockpile at costStockpile value at period startCost of ore addedCost of ore drawn (at average cost)Stockpiles and metal inventories · All minesCosts deferred to the stockpile (released if negative)Cost of ore addedCost of ore drawn (at average cost)Stockpiles and metal inventories · All minesOre stockpile at period endOre stockpile at period startOre mined (direct feed to the plant)from mining and processingOre processed (drawn from the stockpile)
- What it invests in3 formulasMine assets and depreciation · All minesMine capital expenditureMine development capexfrom development and first productionSustaining capexGrowth capexMine assets and depreciation · All minesDepreciation and amortisation (units of production)Opening net book valueMine capital expenditureShare of remaining reserves minedMine assets and depreciation · All minesClosing net book valueOpening net book valueMine capital expenditureDepreciation and amortisation (units of production)
- How it is funded3 formulasDebtRepaymentsScheduled repaymentsPrepayments from an equity raise and the cash sweepDebtClosing balanceOpening balanceDrawdownsRepaymentsDebtInterest expenseOpening balanceAll-in interest rateshare of the year
- How profit becomes cash3 formulasWorking capitalTrade receivablesRevenuefrom statementsDebtor daysDays in periodWorking capitalInventoryDirect costs (positive)from statementsInventory daysDays in periodWorking capitalTrade payablesCash operating costs (positive)from statementsCreditor daysDays in period
22 parts, each one tested.
Every part is a tested building block with its own checks: yours is put together from the ones your business needs.
- CPI forecastConsensus curve with long-run anchor
- Exchange rate (US dollar)Exchange rate by financial year
- Corporate costsFixed cost base indexed to CPI
- Working capitalFull working capital
- Income taxCorporate rate with tax losses
- DebtAmortising term loan
- Equity raisingDistribution reinvestment plan
- Dividends and distributionsPayout of net profit
- Discounted cash flow valuationDCF on free cash flow to the firm
- Multiples valuationEV / EBITDA multiple
- Group unit costs (single-product portfolios)C1, C2 and C3 cost per poundGroup unit costs, realised prices and margins that investors use to compare miners. Only meaningful when every mine sells the same product.
- Key-metric summaryLast-twelve-month and run-rate metrics
- Discount rate (WACC)CAPM at target gearing
- Stockpiles and metal inventoriesOre stockpile at average costOre stockpiles, metal in circuit and on leach pads, and finished product held at cost; the movement adjusts cost of sales.
- Mine registerMine register with resource conversionThe facts every other part of the model builds on — mineable inventory (reserves plus any converted resources), carrying value and mine life.
- Development and first productionInitial capex to first production, then ramp-upPre-production construction capex, first production date and ramp-up to nameplate for new mines and expansions. Development capex feeds the asset base (and so PP&E and investing cash flow).
- Mining and processingRun-of-mine tonnes × plant yield (iron ore, coal)The physical chain from ore and waste mined, through plant throughput, head grade and recovery, to payable product (in units of the mine's own product: ounces, tonnes, dry metric tonnes, pounds) and the reserves remaining.
- Sales and realised pricesPartly hedged gold sales (hedge book at a fixed price)Product sold × realised price, including hedging, offtake terms, quality adjustments and smelter charges. Units sold and prices are per unit of the mine's own product; the market price (spot, or FOB for bulk commodities) is the royalty value basis.
- RoyaltiesHybrid royalty (greater of ad valorem and profit-based)Government royalties, third-party royalties and community payments on each mine's production.
- Site operating costsUnit rates (mining $/t, processing $/t, fixed site G&A)Mining, processing, site administration and (for bulk commodities) rail, port and shipping costs.
- Mine assets and depreciationUnits-of-production depreciation on ore reservesSustaining and growth capex (including capitalised stripping and underground development) and depreciation of mine properties and plant.
- Rehabilitation and closureClosure cost built up over the ore reservesThe rehabilitation and closure provision — build-up or unwinding, progressive rehabilitation spend and final closure. Build-up is an operating charge (direct costs); the unwinding of discount is a non-cash finance cost.
The numbers it tracks.
- 01salt harvested and shipped (Mt)
- 02evaporation versus rainfall
- 03FOB price per tonne
- 04cost per tonne
- 05EBITDA
What it is used for.
- Operating forecastGuide · Financial projections
- Budget and rolling forecastGuide · Cash flow forecast
- ValuationGuide · DCF valuation model
- Lending and credit analysisGuide · Three-statement model
- Project financeGuide · Financial modelling services
- Scenarios and sensitivities
More in producing mines.
- Gold mine financial model
- Copper mine financial model
- Iron ore mine financial model
- Coal mine financial model
- Lithium mine financial model
- Nickel mine financial model
- Zinc and lead mine financial model
- Silver mine financial model
- Platinum group metals mine financial model
- Uranium mine financial model
- Rare earths producer financial model
- Graphite producer financial model
- Vanadium producer financial model
- Mineral sands producer financial model
- Diamond and gemstone mine financial model
- Industrial minerals producer financial model
- Potash and phosphate mine financial model
- Tailings reprocessor financial model
- Diversified miner financial model
Looking for a salt producer financial model template? Ours arrives built for your business, with your figures in it.
See a finished model, sheet by sheetThe sample is built on illustrative figures and describes no real business. Models are calculations prepared from the information you provide. They are not financial advice and must be independently verified. See our terms.