Hydrogen producer financial model, built free.
A three-statement Excel model for a hydrogen producer, built from your own figures and checked to balance.
- Free account
- No card
- Usually ready within the hour
We use generative AI in parts of our process, so mistakes can occur. Every model should be checked by a person before it is relied on. Read more
Converts renewable or grid electricity (or gas with carbon capture) into hydrogen or ammonia sold under offtake contracts, often supported by production credits.
In short
- 01
Three linked statements
Income statement, balance sheet and cash flow, linked in every period.
- 02
Valued two ways
Discounted cash flow and project equity NPV, side by side.
- 03
Monthly to annual
Monthly, quarterly, half-yearly or annual periods, for up to 30 years.
- 04
Checked every period
A Checks sheet shows the balance sheet balances and the cash reconciles.
The sample, as Excel draws it.
Built by the same system and checks as yours, on illustrative figures: every sheet as Excel draws it, or live.
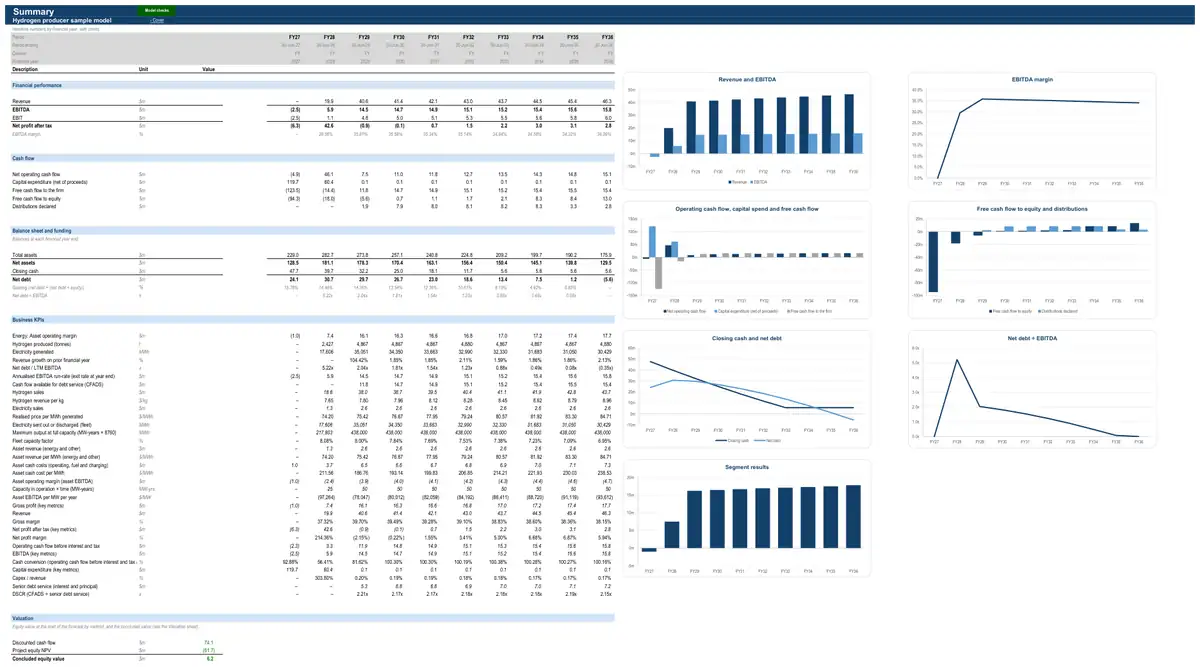
Illustrative figures: the sample describes no real business. The live preview shows values; your model’s Excel file has every formula.
How the model works for a hydrogen producer.
- How it earns revenue3 formulasHydrogen production and sales · All energy assetsElectricity costElectricity used by the electrolyserDelivered electricity priceHydrogen production and sales · All energy assetsElectricity used by the electrolyserInstalled capacityDays in periodElectrolyser utilisationShare of the period in operation (after COD)from development and constructionEnergy revenue · All energy assetsElectricity salesPPA revenueMerchant revenue
- What drives its costs2 formulasOperating costs · All energy assetsOperating costsO&M contractAsset managementLand leaseInsuranceGrid (TUOS) and connection chargesCommunity fundFuel, charging energy and carbon costs · All energy assetsCharging energy costEnergy chargedCharge (off-peak) priceNetwork charge on energy charged
- What it invests in3 formulasAsset base and depreciation · All energy assetsCapital expenditureConstruction capexfrom development and constructionSustaining capexAsset base and depreciation · All energy assetsDepreciationOpening net book valueCapital expenditureShare of the period in operation (after COD) (development and construction)from development and constructionshare of the yearRemaining life at period startAsset base and depreciation · All energy assetsClosing net book valueOpening net book valueCapital expenditureDepreciation
- How it is funded3 formulasDebtRepaymentsScheduled repaymentsPrepayments from an equity raise and the cash sweepDebtClosing balanceOpening balanceDrawdownsRepaymentsDebtInterest expenseOpening balanceAll-in interest rateshare of the year
- How profit becomes cash3 formulasClean energy tax credits · All energy assetsInvestment tax credit earnedPlaced in service in the periodEligible project costCredit rateBonus addersWorking capitalTrade receivablesRevenuefrom statementsDebtor daysDays in periodWorking capitalInventoryDirect costs (positive)from statementsInventory daysDays in period
31 parts, each one tested.
Every part is a tested building block with its own checks: yours is put together from the ones your business needs.
- CPI forecastConsensus curve with long-run anchor
- Corporate costsFixed cost base indexed to CPI
- Working capitalFull working capital
- Income taxCorporate rate with tax losses
- DebtAmortising term loan
- Discounted cash flow valuationDCF on free cash flow to the firm
- Wholesale electricity price curveAdviser price curveThe wholesale electricity price forecast used by the revenue and cost parts that need it.
- Decommissioning and restoration provisionsPresent value with accretionProvisions to remove generation assets, abandon wells and restore sites — recognition, unwinding and spend.
- Energy and utility KPIsGeneration unit metricsThe ratios investors and lenders use to judge energy and utility businesses.
- Key-metric summaryLast-twelve-month and run-rate metrics
- Cash flow available for debt service (CFADS)From free cash flow to the firm
- Debt sizing and sculptingLower of DSCR capacity and maximum gearing
- Senior project debtSculpted repayment
- Reserve accounts (DSRA)DSRA built from operating cash flow
- Cover ratios (DSCR, LLCR, PLCR)Period DSCR with LLCR and PLCR
- Project and equity returnsProject IRR, equity IRR and NPV
- Discount rate (WACC)CAPM at target gearing
- Project timeline and phasesKey dates and durations
- Tax depreciationTax life equal to book life
- Construction funding and drawdownPro rata at the target gearing
- Shareholder loans and the equity splitOrdinary equity only
- Cash flow waterfall and distribution lock-upStandard cascade with lock-up test
- Clean energy tax creditsInvestment tax credit on eligible costProduction and investment tax credits earned by an asset, whether used by the owner, sold to a third party or allocated to a tax equity investor.
- Hydrogen production and salesElectrolyser utilisation and efficiencyHydrogen (or ammonia) output of an electrolyser or reformer and the revenue from selling it, including production credits.
- Asset registerEnergy asset registerThe facts every other part of the model builds on — capacity, opening book value and remaining life.
- GenerationStorage cycles and state of healthElectricity sent out (or discharged) by each asset in each period.
- Energy revenuePPA with merchant tailRevenue from selling electricity (or discharging storage) under contracts and in the wholesale market.
- Operating costsCost lines with escalationSite operating costs — O&M, asset management, land lease, insurance, grid charges and community payments.
- Asset base and depreciationStraight-line depreciation over remaining lifeSustaining and replacement capex and depreciation of each asset's property, plant and equipment.
- Development and constructionTotal capex spread to CODConstruction capex, commercial operation date and ramp-up for new assets, and the development pipeline.
- Fuel, charging energy and carbon costsCharging or pumping energyVariable cost of the energy an asset consumes — gas, coal, charging or pumping electricity, electrolyser power — and its carbon cost.
The numbers it tracks.
- 01hydrogen output (t)
- 02electrolyser utilisation
- 03LCOH per kg
- 04EBITDA
- 05project IRR
What it is used for.
- Project financeGuide · Financial modelling services
- Development feasibilityGuide · Financial modelling services
- Startup and venture fundingGuide · Startup financial model
- Equity capital raisingGuide · Startup financial model
- ValuationGuide · DCF valuation model
- Operating forecastGuide · Financial projections
- Scenarios and sensitivities
More in power generation and renewables.
- Solar and wind farm financial model
- Battery storage project financial model
- Hydro power station financial model
- Gas-fired power station financial model
- Offshore wind farm financial model
- Geothermal generator financial model
- Nuclear generator financial model
- Waste-to-energy plant financial model
- Bioenergy producer financial model
- Renewable energy developer financial model
- Carbon credit project financial model
Looking for a hydrogen producer financial model template? Ours arrives built for your business, with your figures in it.
See a finished model, sheet by sheetThe sample is built on illustrative figures and describes no real business. Models are calculations prepared from the information you provide. They are not financial advice and must be independently verified. See our terms.