Metal fabricator financial model, built free.
A three-statement Excel model for a steel and metal fabricator, built from your own figures and checked to balance.
- Free account
- No card
- Usually ready within the hour
We use generative AI in parts of our process, so mistakes can occur. Every model should be checked by a person before it is relied on. Read more
Cuts, welds, coats and assembles structural steel, plate and sheet-metal work for construction, mining and infrastructure projects, priced per tonne or per contract with steel costs passed through.
In short
- 01
Three linked statements
Income statement, balance sheet and cash flow, linked in every period.
- 02
Valued two ways
Discounted cash flow and trading multiples, side by side.
- 03
Monthly to annual
Monthly, quarterly, half-yearly or annual periods, for up to 30 years.
- 04
Checked every period
A Checks sheet shows the balance sheet balances and the cash reconciles.
The sample, as Excel draws it.
Built by the same system and checks as yours: its structure and its inputs, ready for your own figures.
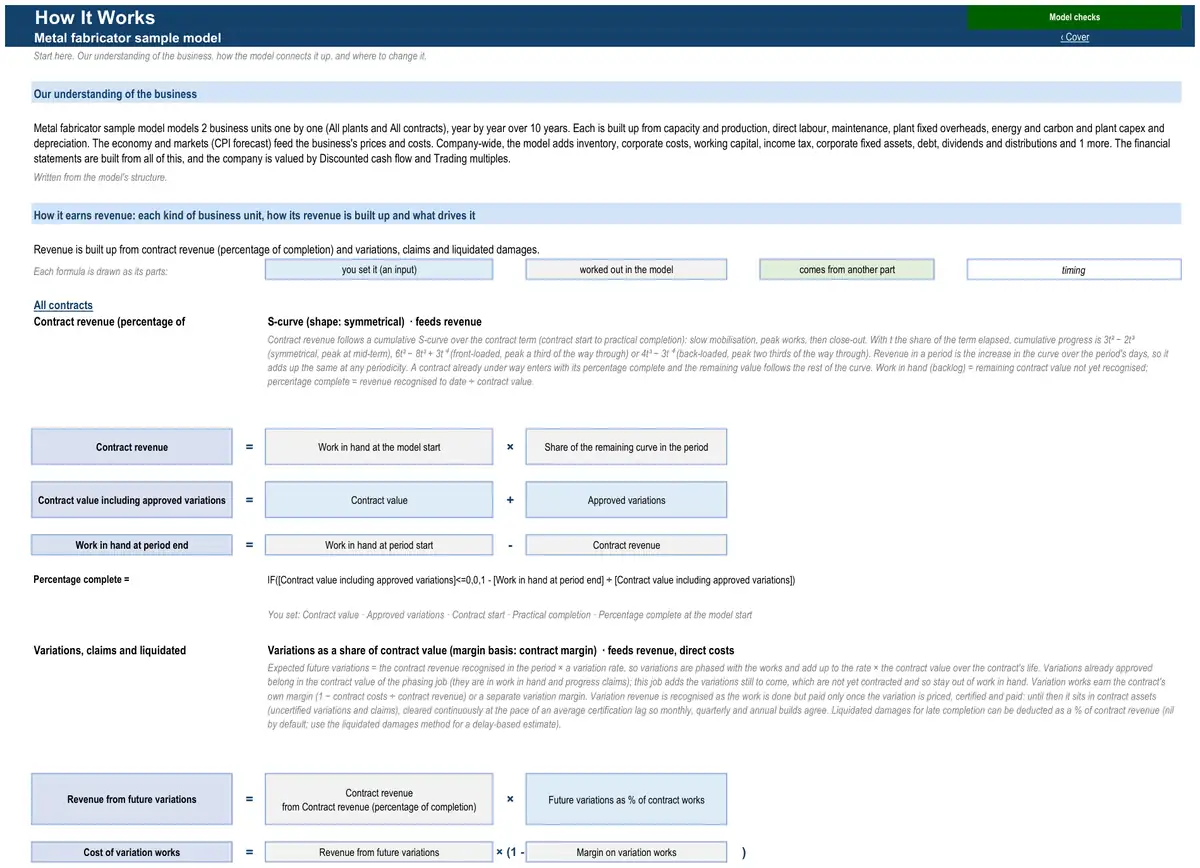
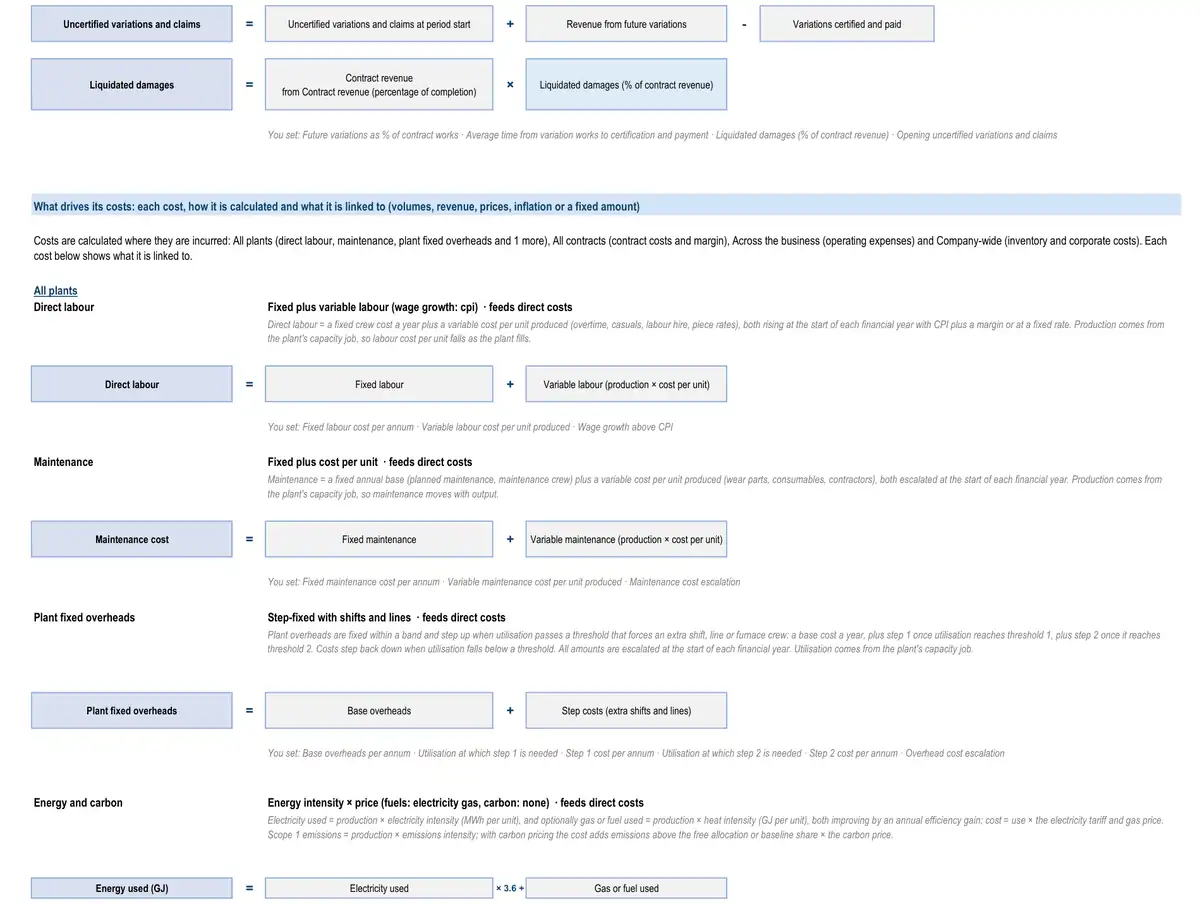
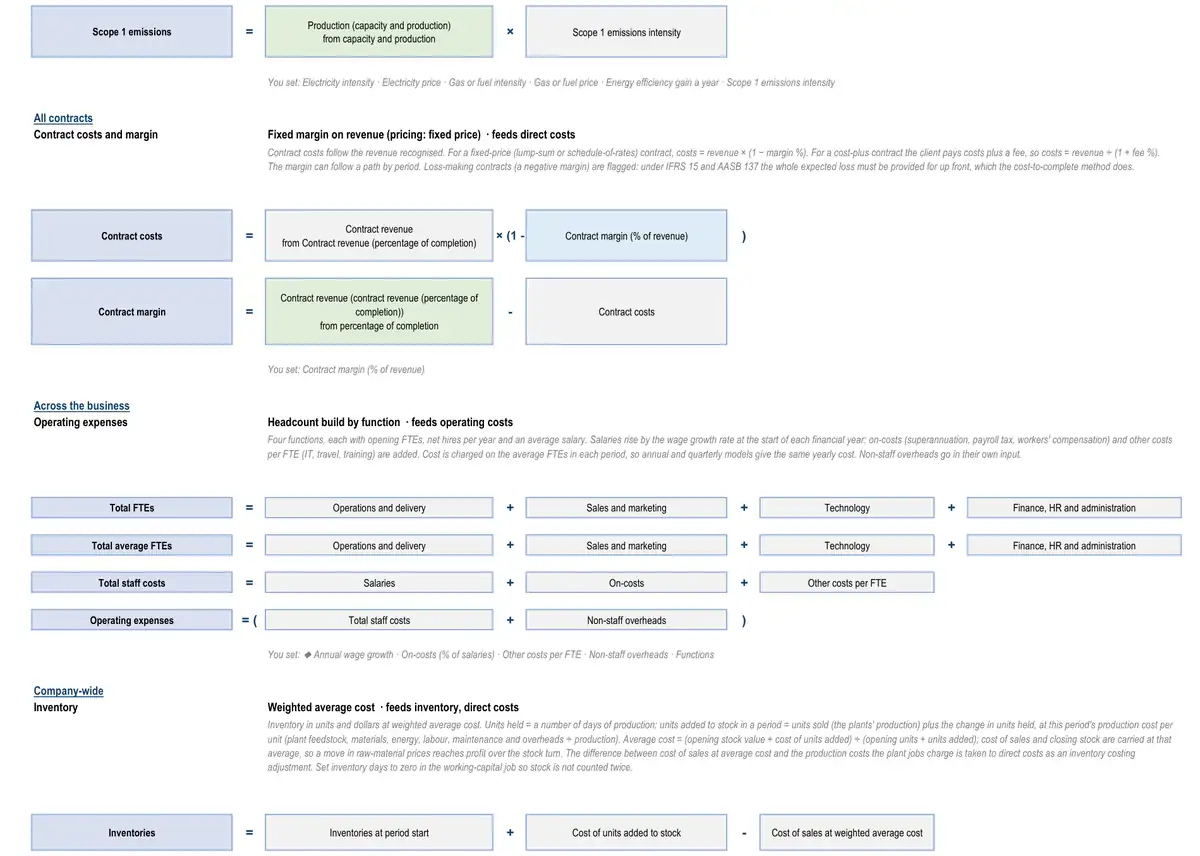
The sample describes no real business. Yours is calibrated to your own figures, so its results are your business’s.
How the model works for a metal fabricator.
- How it earns revenue3 formulasContract revenue (percentage of completion) · All contractsContract revenueWork in hand at the model startShare of the remaining curve in the periodContract revenue (percentage of completion) · All contractsContract value including approved variationsContract valueApproved variationsContract revenue (percentage of completion) · All contractsWork in hand at period endWork in hand at period startContract revenue
- What drives its costs3 formulasDirect labour · All plantsDirect labourFixed labourVariable labour (production × cost per unit)Maintenance · All plantsMaintenance costFixed maintenanceVariable maintenance (production × cost per unit)Plant fixed overheads · All plantsPlant fixed overheadsBase overheadsStep costs (extra shifts and lines)
- What it invests in3 formulasPlant capex and depreciation · All plantsPlant capital expenditureSustaining capexGrowth capexPlant capex and depreciation · All plantsPlant depreciationDepreciation of existing assetsDepreciation of sustaining additionsProject 1 depreciation (from commissioning)from from commissioningProject 2 depreciation (from commissioning)from from commissioningProject 3 depreciation (from commissioning)from from commissioningPlant capex and depreciation · All plantsClosing net book valueOpening net book valuePlant capital expenditurePlant depreciation
- How it is funded3 formulasDebtRepaymentsScheduled repaymentsPrepayments from an equity raise and the cash sweepDebtClosing balanceOpening balanceDrawdownsRepaymentsDebtInterest expenseOpening balanceAll-in interest rateshare of the year
- How profit becomes cash3 formulasProgress claims, retentions and contract balances · All contractsRetention security held at period endRetention security held at period startRetention security on the period's claimsRetention security releasedProgress claims, retentions and contract balances · All contractsCash retentions receivableCash retentions at period startRetentions withheld from claimsRetentions released (cash received)Working capitalTrade receivablesRevenuefrom statementsDebtor daysDays in period
25 parts, each one tested.
Every part is a tested building block with its own checks: yours is put together from the ones your business needs.
- CPI forecastConsensus curve with long-run anchor
- Operating expensesHeadcount build by function
- Corporate costsFixed cost base indexed to CPI
- Working capitalFull working capital
- Income taxCorporate rate with tax losses
- Corporate fixed assetsStraight-line over remaining life
- DebtAmortising term loan
- Dividends and distributionsPayout of net profit
- Discounted cash flow valuationDCF on free cash flow to the firm
- Multiples valuationEV / EBITDA multiple
- LeasesLease register
- InventoryWeighted average costRaw materials, work-in-progress and finished goods held to support production and sales (used in place of the inventory part of working capital), and the cost-of-sales effect of the costing method and stock provisions.
- Key-metric summaryLast-twelve-month and run-rate metrics
- Discount rate (WACC)CAPM at target gearing
- Terminal valuePerpetuity growth on normalised cash flow
- Capacity and productionOperating days × daily rateHow much a plant can make and how much it does make, from capacity, operating time, utilisation and yield.
- Direct labourFixed plus variable labourWages and on-costs of the production workforce at each plant.
- MaintenanceFixed plus cost per unitRoutine maintenance and periodic shutdowns needed to keep plant running.
- Plant fixed overheadsStep-fixed with shifts and linesSite costs that do not vary with output: site management and supervision, quality, site services, insurance, rates and other production overheads of each plant.
- Plant capex and depreciationSustaining capex plus growth projectsSustaining and expansion capital expenditure on plant, and the depreciation and book value that follow.
- Energy and carbonEnergy intensity × priceElectricity, gas and fuel used by a plant, and the cost of the carbon it emits.
- Contract revenue (percentage of completion)S-curveHow each contract's value is recognised as revenue over time, and the work still to do (backlog).
- Contract costs and marginFixed margin on revenueThe cost of delivering each contract and the margin recognised, including losses on onerous contracts.
- Progress claims, retentions and contract balancesClaim and payment lag with retentionsWhen contract revenue turns into cash: progress claims, retentions, advance payments and contract assets and liabilities.
- Variations, claims and liquidated damagesVariations as a share of contract valueChanges to each contract's value from approved and unapproved variations and claims (recognised only when highly probable), and damages payable for late completion.
The numbers it tracks.
- 01tonnes fabricated
- 02revenue per tonne
- 03shop utilisation
- 04contract margin
- 05EBITDA margin
More in manufacturing and machinery.
- Discrete manufacturer financial model
- Contract manufacturer financial model
- Capital equipment manufacturer financial model
- Industrial components manufacturer financial model
- Robotics and automation manufacturer financial model
- Electrical equipment manufacturer financial model
- HVAC manufacturer financial model
- Heavy equipment manufacturer financial model
- 3D printing company financial model
- Industrial conglomerate financial model
Looking for a metal fabricator financial model template? Ours arrives built for your business, with your figures in it.
See a finished model, sheet by sheetThe sample is built on illustrative figures and describes no real business. Models are calculations prepared from the information you provide. They are not financial advice and must be independently verified. See our terms.