Port authority financial model, built free.
A three-statement Excel model for a landlord port owner or port authority, built from your own figures and checked to balance.
- Free account
- No card
- Usually ready within the hour
We use generative AI in parts of our process, so mistakes can occur. Every model should be checked by a person before it is relied on. Read more
Owns port land, channels, breakwaters and common-user wharves (often under a long privatisation lease), earning port dues and wharfage from shipping lines and cargo owners and long-term rent from terminal operators, with prices sometimes monitored or regulated.
In short
- 01
Three linked statements
Income statement, balance sheet and cash flow, linked in every period.
- 02
Valued two ways
Discounted cash flow and trading multiples, side by side.
- 03
Monthly to annual
Monthly, quarterly, half-yearly or annual periods, for up to 30 years.
- 04
Checked every period
A Checks sheet shows the balance sheet balances and the cash reconciles.
The sample, as Excel draws it.
Built by the same system and checks as yours, on illustrative figures: every sheet as Excel draws it, or live.
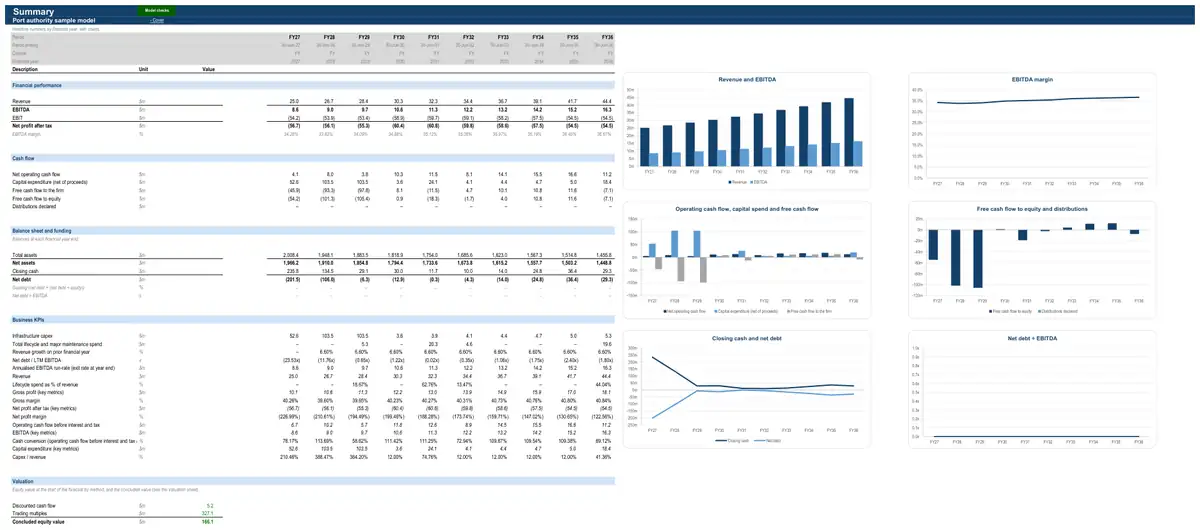
Illustrative figures: the sample describes no real business. The live preview shows values; your model’s Excel file has every formula.
How the model works for a port authority.
- How it earns revenue1 formulaRevenue (top-down) · The businessRevenueUnits soldAverage price
- What drives its costs3 formulasDirect costs (top-down) · The businessCost of salesRevenuefrom statementsGross marginLifecycle, major maintenance and handback · The businessMajor maintenance expense (works plus provision movement)Major maintenance works paidProvision requiredProvision at period startLifecycle, major maintenance and handback · The businessProvision at period endProvision at period startMajor maintenance expense (works plus provision movement)Major maintenance works paid
- What it invests in3 formulasInfrastructure assets and capex programme · The businessInfrastructure capexSustaining capexGrowth capexInfrastructure assets and capex programme · The businessInfrastructure depreciationDepreciation of existing assetsDepreciation of sustaining additionsProject 1 depreciation (from commissioning)from from commissioningProject 2 depreciation (from commissioning)from from commissioningProject 3 depreciation (from commissioning)from from commissioningInfrastructure assets and capex programme · The businessClosing net book valueOpening net book valueInfrastructure capexInfrastructure depreciation
- How it is funded3 formulasDebtRepaymentsScheduled repaymentsPrepayments from an equity raise and the cash sweepDebtClosing balanceOpening balanceDrawdownsRepaymentsDebtInterest expenseOpening balanceAll-in interest rateshare of the year
- How profit becomes cash3 formulasWorking capitalTrade receivablesRevenuefrom statementsDebtor daysDays in periodWorking capitalInventoryDirect costs (positive)from statementsInventory daysDays in periodWorking capitalTrade payablesCash operating costs (positive)from statementsCreditor daysDays in period
19 parts, each one tested.
Every part is a tested building block with its own checks: yours is put together from the ones your business needs.
- CPI forecastConsensus curve with long-run anchor
- Revenue (top-down)Price × volume
- Direct costs (top-down)Gross margin %
- Corporate costsFixed cost base indexed to CPI
- Working capitalFull working capital
- Income taxCorporate rate with tax losses
- DebtAmortising term loan
- Dividends and distributionsPayout of net profit
- Discounted cash flow valuationDCF on free cash flow to the firm
- Multiples valuationEV / EBITDA multiple
- Interest-rate hedgingHedged share at a fixed rate
- Infrastructure assets and capex programmeSustaining capex plus growth projectsOwned or long-lease infrastructure — runways, terminals, berths, track, rolling stock, stadiums — with its capex programme, depreciation by asset class and optional revaluation.
- Lifecycle, major maintenance and handbackComponent replacement schedulePeriodic renewal of concession and PPP assets (resurfacing, mechanical and electrical replacement), reserves and provisions for it, and works needed to hand the asset back.
- Concession asset and grantor paymentsIntangible amortised to concession endHow the right to operate a concession (toll road, airport, port, PPP) sits on the balance sheet and is used up over the concession life, including fees paid to the grantor.
- Key-metric summaryLast-twelve-month and run-rate metrics
- Covenant tests and headroomLVR, gearing and ICR for property
- Discount rate (WACC)CAPM at target gearing
- Terminal valuePerpetuity growth on normalised cash flow
- Interest-rate forecastMarket forward curve
The numbers it tracks.
- 01trade volumes
- 02revenue by charge type
- 03tenant rent
- 04EBITDA margin
- 05capex programme
- 06net debt / EBITDA
What it is used for.
- Operating forecastGuide · Financial projections
- Budget and rolling forecastGuide · Cash flow forecast
- ValuationGuide · DCF valuation model
- Lending and credit analysisGuide · Three-statement model
- Development feasibilityGuide · Financial modelling services
- Asset acquisition
More in roads, airports and ports.
- Toll road operator financial model
- Car park operator financial model
- Airport operator financial model
- General aviation airport financial model
- Airport ground handling company financial model
- Airport retail concession financial model
- Port and terminal operator financial model
- Towage and marine services financial model
Looking for a port authority financial model template? Ours arrives built for your business, with your figures in it.
See a finished model, sheet by sheetThe sample is built on illustrative figures and describes no real business. Models are calculations prepared from the information you provide. They are not financial advice and must be independently verified. See our terms.