Health insurer financial model, built free.
A three-statement Excel model for a health insurer or managed care organisation, built from your own figures and checked to balance.
- Free account
- No card
- Usually ready within the hour
We use generative AI in parts of our process, so mistakes can occur. Every model should be checked by a person before it is relied on. Read more
Private health fund or managed care plan collecting premiums per member (hospital and extras cover; or commercial, Medicare Advantage and Medicaid plans) and paying hospital, medical and drug benefits, earning the gap between premium and benefits and management expenses.
In short
- 01
Three linked statements
Income statement, balance sheet and cash flow, linked in every period.
- 02
Valued two ways
Discounted cash flow and trading multiples, side by side.
- 03
Monthly to annual
Monthly, quarterly, half-yearly or annual periods, for up to 30 years.
- 04
Checked every period
A Checks sheet shows the balance sheet balances and the cash reconciles.
The sample, as Excel draws it.
Built by the same system and checks as yours, on illustrative figures: every sheet as Excel draws it, or live.
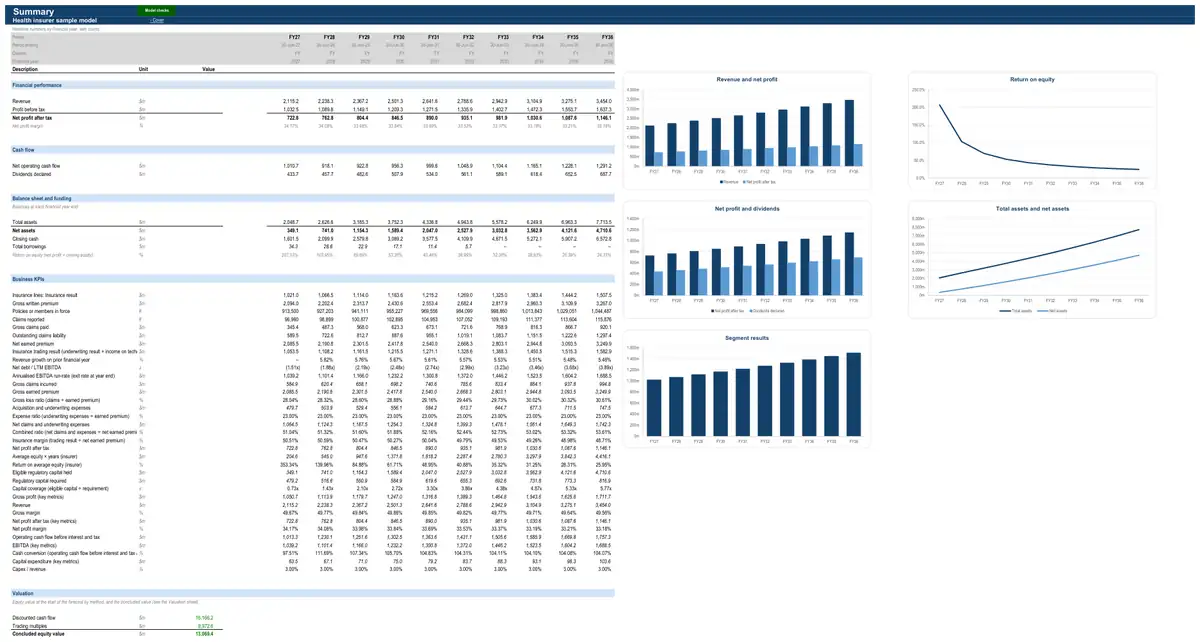
Illustrative figures: the sample describes no real business. The live preview shows values; your model’s Excel file has every formula.
How the model works for a health insurer.
- How it earns revenue3 formulasPremiums · All insurance linesClosing unearned premiumGross earned premiumshare of the yearDays of premium paid aheadPremiums · All insurance linesClosing membersOpening membersNet growth in membersPremiums · All insurance linesMember monthsOpening membersClosing membersshare of the year
- What drives its costs3 formulasClaims and loss ratios · All insurance linesClosing exposuresOpening exposuresGrowth in exposuresClaims and loss ratios · All insurance linesGross claims incurredClaims reportedAverage claim sizeClaims and loss ratios · All insurance linesClaims reportedExposure-years (average exposures × years)Claim frequency (claims per exposure a year)
- What it invests in3 formulasCorporate fixed assetsCapital expenditureRevenuefrom statementsCapex as % of revenueAdditional planned capexCorporate fixed assetsDepreciationDepreciation of the opening asset baseDepreciation of new capexCorporate fixed assetsClosing net book valueOpening net book valueCapital expenditureDepreciation
- How it is funded3 formulasDebtRepaymentsScheduled repaymentsPrepayments from an equity raise and the cash sweepDebtClosing balanceOpening balanceDrawdownsRepaymentsDebtInterest expenseOpening balanceAll-in interest rateshare of the year
- How profit becomes cash3 formulasClaims reserves · All insurance linesClaims paid on claims incurred since the start datePaid in the first year after being incurredPaid in the second yearPaid in the third yearPaid in the fourth yearPaid in the fifth yearPaid in the sixth yearPaid in years seven to tenClaims reserves · All insurance linesClosing outstanding claimsOpening outstanding claimsGross claims incurredfrom claims and loss ratiosClaims paidClaims reserves · All insurance linesClaims paidClaims paid on claims incurred since the start dateClaims paid from the opening liability
22 parts, each one tested.
Every part is a tested building block with its own checks: yours is put together from the ones your business needs.
- CPI forecastConsensus curve with long-run anchor
- Operating expensesHeadcount build by function
- Corporate costsFixed cost base indexed to CPI
- Working capitalFull working capital
- Income taxCorporate rate with tax losses
- Corporate fixed assetsStraight-line over remaining life
- DebtAmortising term loan
- Equity raisingDistribution reinvestment plan
- Dividends and distributionsPayout of net profit
- Discounted cash flow valuationDCF on free cash flow to the firm
- Multiples valuationEV / EBITDA multiple
- Investment incomeAsset allocation × expected returnsReturns on the investment portfolio backing technical reserves and shareholders' funds.
- Solvency capitalRisk charges buildRegulatory capital required (prescribed capital amount or solvency capital requirement) and the coverage held, driving dividends and raisings.
- Key-metric summaryLast-twelve-month and run-rate metrics
- Case selectionStackable stress toggles
- Value per shareTreasury-stock method
- Interest-rate forecastMarket forward curve
- Enterprise value to equity bridgeNet debt at the valuation date
- PremiumsMembers × premium per member per monthGross written premium and how it is earned over the cover period, leaving an unearned premium liability.
- Claims and loss ratiosFrequency × severityClaims incurred on earned premium — attritional, large and catastrophe claims, or mortality and morbidity for life risk.
- Claims reservesPayment patternOutstanding claims liability built from claims incurred, the payment pattern, discounting and the risk adjustment.
- Acquisition and underwriting expensesExpense ratio on earned premiumCommissions, other acquisition costs and the underwriting expenses that make up the expense ratio.
The numbers it tracks.
- 01members
- 02premium per member
- 03benefits per member
- 04medical loss ratio
- 05management expense ratio
- 06net margin
- 07capital coverage
What it is used for.
- Operating forecastGuide · Financial projections
- Budget and rolling forecastGuide · Cash flow forecast
- ValuationGuide · DCF valuation model
- Merger or acquisition (strategic)Guide · Financial modelling services
- Scenarios and sensitivities
More in insurance.
- General insurer financial model
- Life insurer financial model
- Reinsurer financial model
- Annuity provider financial model
- Underwriting agency (MGA) financial model
- Insurance broker financial model
Looking for a health insurer financial model template? Ours arrives built for your business, with your figures in it.
See a finished model, sheet by sheetThe sample is built on illustrative figures and describes no real business. Models are calculations prepared from the information you provide. They are not financial advice and must be independently verified. See our terms.