Radiology and pathology provider financial model, built free.
A three-statement Excel model for a diagnostic imaging and pathology provider, built from your own figures and checked to balance.
- Free account
- No card
- Usually ready within the hour
We use generative AI in parts of our process, so mistakes can occur. Every model should be checked by a person before it is relied on. Read more
Performs imaging scans or pathology tests paid mostly by Medicare rebates and patient gaps, driven by referral volumes, equipment capacity and fee per service.
In short
- 01
Three linked statements
Income statement, balance sheet and cash flow, linked in every period.
- 02
Valued two ways
Discounted cash flow and trading multiples, side by side.
- 03
Monthly to annual
Monthly, quarterly, half-yearly or annual periods, for up to 30 years.
- 04
Checked every period
A Checks sheet shows the balance sheet balances and the cash reconciles.
The sample, as Excel draws it.
Built by the same system and checks as yours, on illustrative figures: every sheet as Excel draws it, or live.
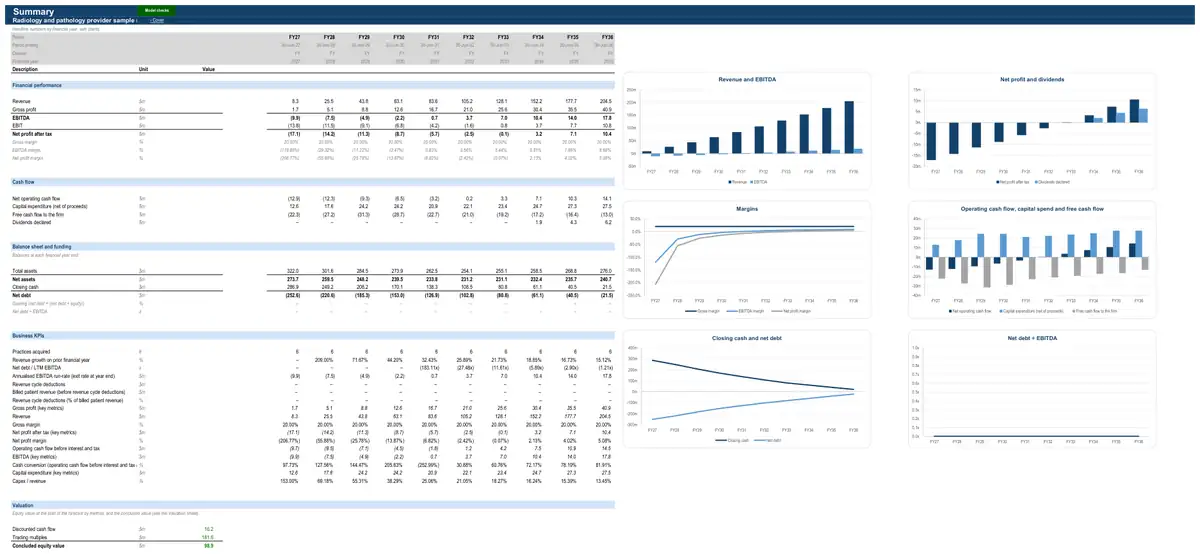
Illustrative figures: the sample describes no real business. The live preview shows values; your model’s Excel file has every formula.
How the model works for a radiology and pathology provider.
- How it earns revenue3 formulasPractice and site acquisitions · The businessDirect costs of acquired practicesRevenue from acquired practicesEBITDA of acquired practicesPractice and site acquisitions · The businessClosing deferred considerationOpening deferred considerationConsideration deferredDeferred consideration paidPractice and site acquisitions · The businessPayments for acquisitions (upfront and deferred)Consideration for practices acquiredConsideration deferredDeferred consideration paid
- What drives its costs3 formulasOperating expenses · The businessTotal FTEsOperations and deliverySales and marketingTechnologyFinance, HR and administrationOperating expenses · The businessTotal average FTEsOperations and deliverySales and marketingTechnologyFinance, HR and administrationOperating expenses · The businessTotal staff costsSalariesOn-costsOther costs per FTE
- What it invests in3 formulasCorporate fixed assetsCapital expenditureRevenuefrom statementsCapex as % of revenueAdditional planned capexCorporate fixed assetsDepreciationDepreciation of the opening asset baseDepreciation of new capexCorporate fixed assetsClosing net book valueOpening net book valueCapital expenditureDepreciation
- How it is funded3 formulasDebtRepaymentsScheduled repaymentsPrepayments from an equity raise and the cash sweepDebtClosing balanceOpening balanceDrawdownsRepaymentsDebtInterest expenseOpening balanceAll-in interest rateshare of the year
- How profit becomes cash3 formulasWorking capitalTrade receivablesRevenuefrom statementsDebtor daysDays in periodWorking capitalInventoryDirect costs (positive)from statementsInventory daysDays in periodWorking capitalTrade payablesCash operating costs (positive)from statementsCreditor daysDays in period
18 parts, each one tested.
Every part is a tested building block with its own checks: yours is put together from the ones your business needs.
- CPI forecastConsensus curve with long-run anchor
- Operating expensesHeadcount build by function
- Corporate costsFixed cost base indexed to CPI
- Working capitalFull working capital
- Income taxCorporate rate with tax losses
- Corporate fixed assetsStraight-line over remaining life
- DebtAmortising term loan
- Equity raisingDistribution reinvestment plan
- Dividends and distributionsPayout of net profit
- Discounted cash flow valuationDCF on free cash flow to the firm
- Multiples valuationEV / EBITDA multiple
- Practice and site acquisitionsAcquisitions per year × size × multipleRoll-up acquisitions of practices, clinics, imaging sites or pharmacies — consideration paid, goodwill, and the revenue and costs acquired.
- Medical equipment capex and replacementEquipment register with replacement datesCapex, depreciation and book value of major medical equipment — imaging modalities, linear accelerators, dialysis machines, theatre and laboratory equipment — replaced on its own cycle.
- Revenue cycle deductionsExpected collection rate by payerThe step from billed or contracted revenue to what is actually collected — contractual allowances on gross charges, implicit price concessions on patient balances, claim denials and third-party settlements — for providers billing insurers and patients claim by claim.
- LeasesLease register
- Key-metric summaryLast-twelve-month and run-rate metrics
- Covenant tests and headroomLVR, gearing and ICR for property
- Case selectionStackable stress toggles
The numbers it tracks.
- 01services
- 02revenue per service
- 03modality utilisation
- 04labour cost ratio
- 05EBITDA margin
What it is used for.
- Operating forecastGuide · Financial projections
- Budget and rolling forecastGuide · Cash flow forecast
- ValuationGuide · DCF valuation model
- Merger or acquisition (strategic)Guide · Financial modelling services
- Leveraged buyout (private equity)Guide · Financial modelling services
- Lending and credit analysisGuide · Three-statement model
- Scenarios and sensitivities
More in clinics and practices.
- Medical centre financial model
- Dental and allied health practice financial model
- Veterinary clinic financial model
- Specialist medical practice financial model
- IVF clinic financial model
- Pharmacy financial model
- Telehealth provider financial model
- Primary health network financial model
Looking for a radiology and pathology provider financial model template? Ours arrives built for your business, with your figures in it.
Running a small business? Read what goes into a small business financial model.
See a finished model, sheet by sheetThe sample is built on illustrative figures and describes no real business. Models are calculations prepared from the information you provide. They are not financial advice and must be independently verified. See our terms.