Professional sports club financial model, built free.
A three-statement Excel model for a professional sports club, built from your own figures and checked to balance.
- Free account
- No card
- Usually ready within the hour
We use generative AI in parts of our process, so mistakes can occur. Every model should be checked by a person before it is relied on. Read more
Fields a team in a professional league, earning membership, matchday, sponsorship and merchandise revenue plus central broadcast distributions from the league, and spends most of it on player payments within a salary cap or cost-control rules, sometimes also trading player registrations.
In short
- 01
Three linked statements
Income statement, balance sheet and cash flow, linked in every period.
- 02
Valued two ways
Discounted cash flow and trading multiples, side by side.
- 03
Monthly to annual
Monthly, quarterly, half-yearly or annual periods, for up to 30 years.
- 04
Checked every period
A Checks sheet shows the balance sheet balances and the cash reconciles.
The sample, as Excel draws it.
Built by the same system and checks as yours, on illustrative figures: every sheet as Excel draws it, or live.
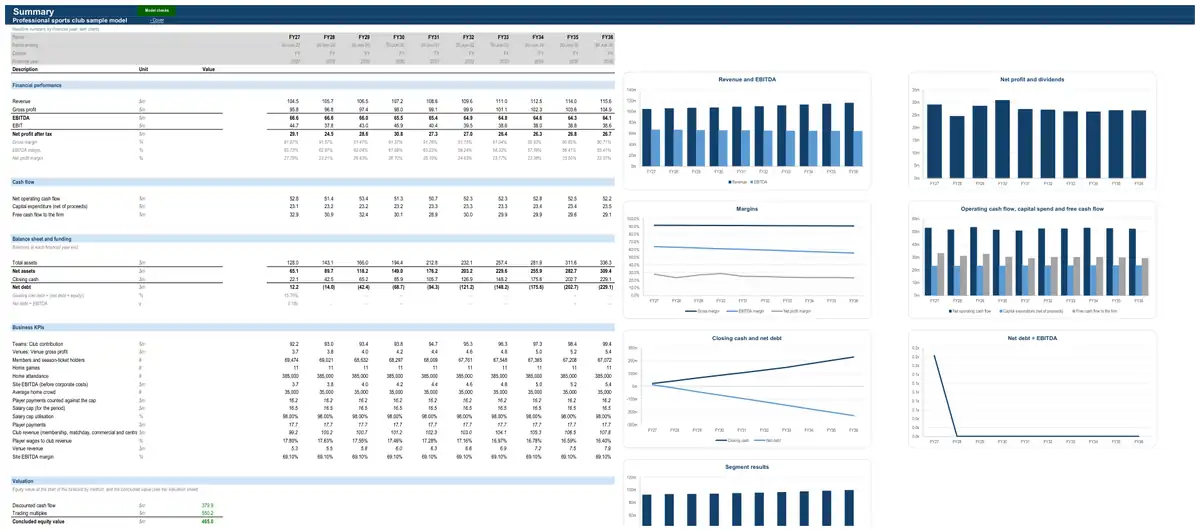
Illustrative figures: the sample describes no real business. The live preview shows values; your model’s Excel file has every formula.
How the model works for a professional sports club.
- How it earns revenue3 formulasMembership and season tickets · All teamsMembership revenueMember-years (average members × years)Average yield per member a yearMembership and season tickets · All teamsClosing membersOpening membersNew members and waiting-list conversionsMembers lapsedMatchday revenue and costs · All teamsMatchday revenueGate receiptsHospitality and catering
- What drives its costs3 formulasPlayer payments and salary cap · All teamsPlayer paymentsPayments counted against the capPayments outside the capPlayer payments and salary cap · All teamsPayments counted against the capSalary cap for the periodCap utilisationCost of goods sold and content costs · All venuesCost of goods sold and content costsBeverage cost of salesFood cost of salesMerchandise cost of salesContent costs on admissions
- What it invests in3 formulasCorporate fixed assetsCapital expenditureRevenuefrom statementsCapex as % of revenueAdditional planned capexCorporate fixed assetsDepreciationDepreciation of the opening asset baseDepreciation of new capexCorporate fixed assetsClosing net book valueOpening net book valueCapital expenditureDepreciation
- How it is funded3 formulasDebtRepaymentsScheduled repaymentsPrepayments from an equity raise and the cash sweepDebtClosing balanceOpening balanceDrawdownsRepaymentsDebtInterest expenseOpening balanceAll-in interest rateshare of the year
- How profit becomes cash3 formulasWorking capitalTrade receivablesRevenuefrom statementsDebtor daysDays in periodWorking capitalInventoryDirect costs (positive)from statementsInventory daysDays in periodWorking capitalTrade payablesCash operating costs (positive)from statementsCreditor daysDays in period
24 parts, each one tested.
Every part is a tested building block with its own checks: yours is put together from the ones your business needs.
- CPI forecastConsensus curve with long-run anchor
- Exchange rate (US dollar)Exchange rate by financial year
- Operating expensesHeadcount build by function
- Corporate costsFixed cost base indexed to CPI
- Working capitalFull working capital
- Income taxCorporate rate with tax losses
- Corporate fixed assetsStraight-line over remaining life
- DebtAmortising term loan
- Equity raisingDistribution reinvestment plan
- Discounted cash flow valuationDCF on free cash flow to the firm
- Multiples valuationEV / EBITDA multiple
- LeasesLease register
- Customer deposits, deferred revenue and loyaltyDeferred revenue as days of revenue
- Membership and season ticketsRenewals and new membersClub members and season-ticket holders, the revenue they pay, and memberships sold before the season starts.
- Matchday revenue and costsHome games × crowd × yieldGate receipts, corporate hospitality and catering from home games, net of stadium and game-day costs.
- Sponsorship and merchandiseSponsorship contractsSponsorship, partnerships and merchandise revenue, and the cost of delivering them.
- Central distributions and prize moneyEqual share plus merit and facility feesThe club's share of league broadcast and commercial income, special distributions and prize money.
- Player payments and salary capSalary cap × utilisationPayments to players (and football department staff) within the salary cap, cost-control rules or collective agreement.
- Player registrations and transfersNet spend per windowTransfer fees capitalised as intangible assets and amortised over each player's contract, instalments owed, and profit on selling players.
- Club KPIs and cost-control testsSalary cap complianceCap compliance, wages to revenue and football cost-control tests.
- Venue registerOpening date, closing date and capacity
- Food, beverage and secondary spend revenueCovers × average spend per head
- Cost of goods sold and content costsMargin by revenue stream
- Venue revenue and site EBITDA
The numbers it tracks.
- 01members
- 02crowds
- 03commercial revenue
- 04central distributions
- 05player payments to cap
- 06wages to revenue
- 07profit on player trading
- 08operating result
- 09cash reserves
What it is used for.
- Budget and rolling forecastGuide · Cash flow forecast
- Operating forecastGuide · Financial projections
- Lending and credit analysisGuide · Three-statement model
- Equity capital raisingGuide · Startup financial model
- Merger or acquisition (strategic)Guide · Financial modelling services
- Scenarios and sensitivities
More in sport and talent.
- Sports league financial model
- Talent management agency financial model
- Esports and creator studio financial model
Looking for a professional sports club financial model template? Ours arrives built for your business, with your figures in it.
See a finished model, sheet by sheetThe sample is built on illustrative figures and describes no real business. Models are calculations prepared from the information you provide. They are not financial advice and must be independently verified. See our terms.