Book publisher financial model, built free.
A three-statement Excel model for a book publisher, built from your own figures and checked to balance.
- Free account
- No card
- Usually ready within the hour
We use generative AI in parts of our process, so mistakes can occur. Every model should be checked by a person before it is relied on. Read more
Acquires rights from authors against advances and royalties, publishes frontlist and backlist titles in print, ebook and audio across trade and education imprints, sells them to retailers on sale-or-return terms, and licenses subsidiary rights.
In short
- 01
Three linked statements
Income statement, balance sheet and cash flow, linked in every period.
- 02
Valued two ways
Discounted cash flow and trading multiples, side by side.
- 03
Monthly to annual
Monthly, quarterly, half-yearly or annual periods, for up to 30 years.
- 04
Checked every period
A Checks sheet shows the balance sheet balances and the cash reconciles.
The sample, as Excel draws it.
Built by the same system and checks as yours: its structure and its inputs, ready for your own figures.
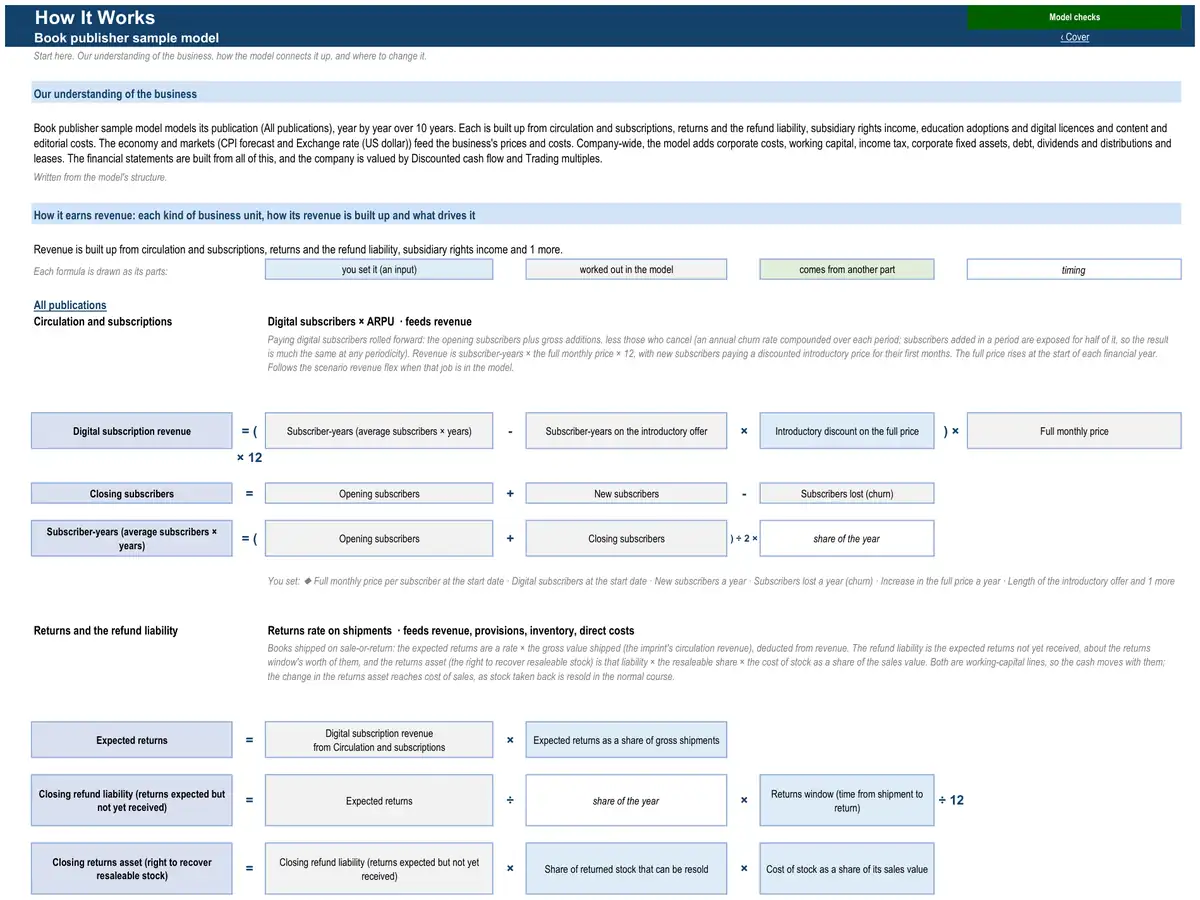
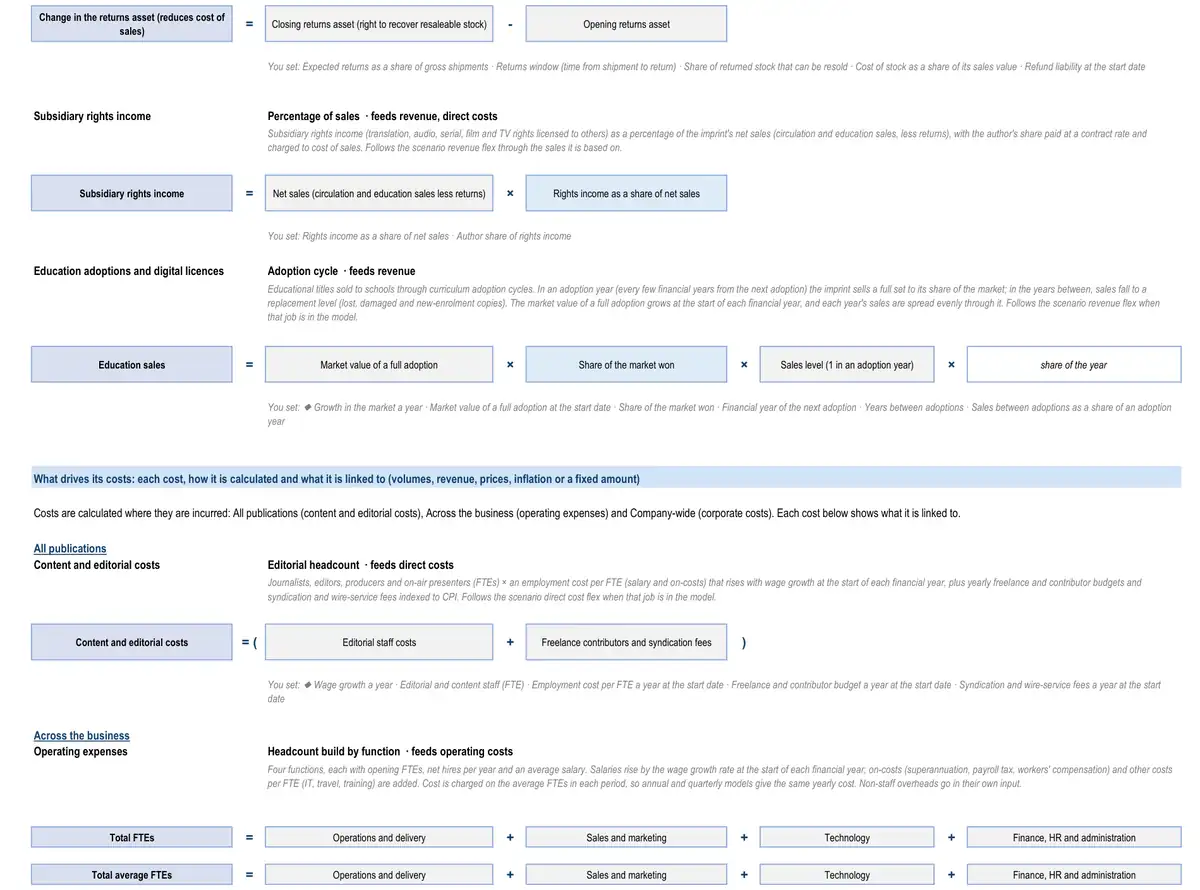
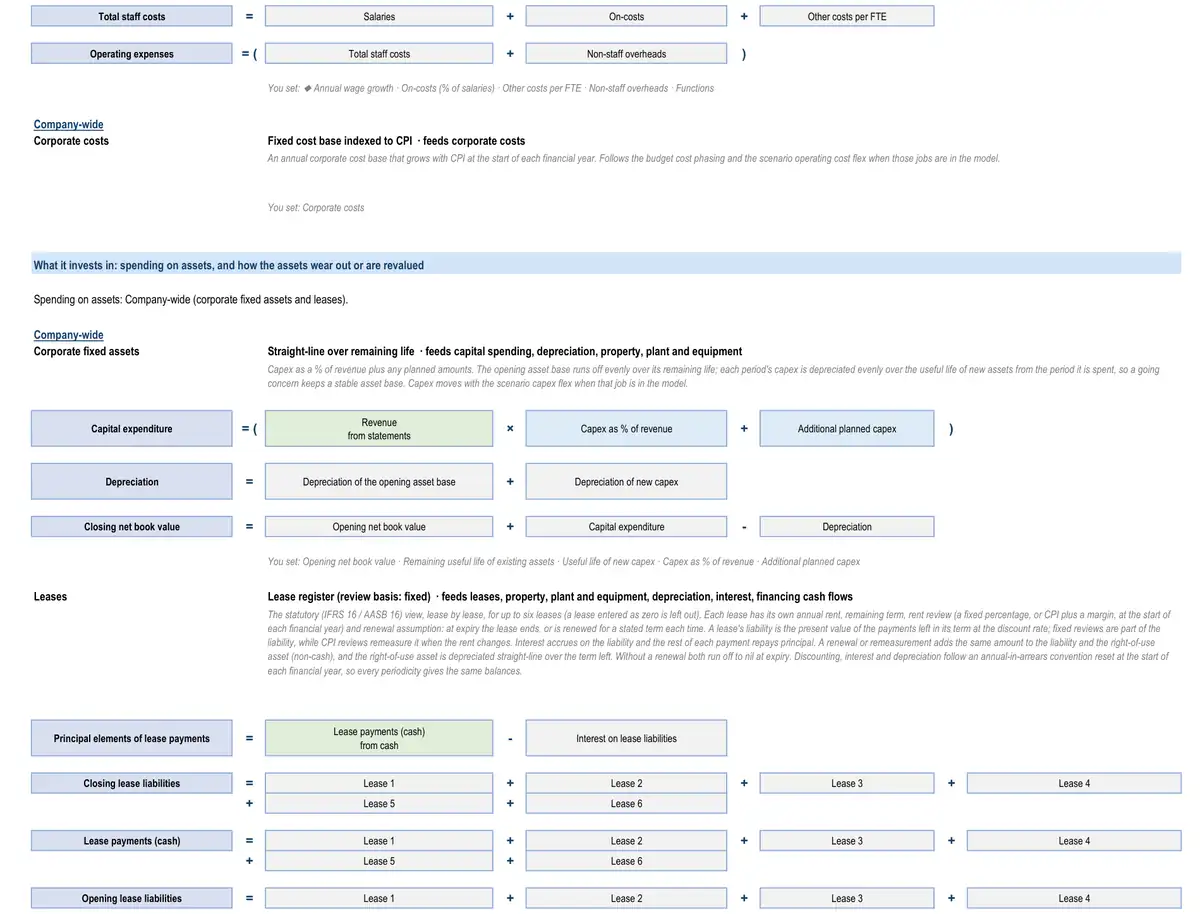
The sample describes no real business. Yours is calibrated to your own figures, so its results are your business’s.
How the model works for a book publisher.
- How it earns revenue3 formulasCirculation and subscriptions · All publicationsDigital subscription revenueSubscriber-years (average subscribers × years)Subscriber-years on the introductory offerIntroductory discount on the full priceFull monthly priceCirculation and subscriptions · All publicationsClosing subscribersOpening subscribersNew subscribersSubscribers lost (churn)Circulation and subscriptions · All publicationsSubscriber-years (average subscribers × years)Opening subscribersClosing subscribersshare of the year
- What drives its costs3 formulasContent and editorial costs · All publicationsContent and editorial costsEditorial staff costsFreelance contributors and syndication feesOperating expenses · Across the businessTotal FTEsOperations and deliverySales and marketingTechnologyFinance, HR and administrationOperating expenses · Across the businessTotal average FTEsOperations and deliverySales and marketingTechnologyFinance, HR and administration
- What it invests in3 formulasCorporate fixed assetsCapital expenditureRevenuefrom statementsCapex as % of revenueAdditional planned capexCorporate fixed assetsDepreciationDepreciation of the opening asset baseDepreciation of new capexCorporate fixed assetsClosing net book valueOpening net book valueCapital expenditureDepreciation
- How it is funded3 formulasDebtRepaymentsScheduled repaymentsPrepayments from an equity raise and the cash sweepDebtClosing balanceOpening balanceDrawdownsRepaymentsDebtInterest expenseOpening balanceAll-in interest rateshare of the year
- How profit becomes cash3 formulasWorking capitalTrade receivablesRevenuefrom statementsDebtor daysDays in periodWorking capitalInventoryDirect costs (positive)from statementsInventory daysDays in periodWorking capitalTrade payablesCash operating costs (positive)from statementsCreditor daysDays in period
17 parts, each one tested.
Every part is a tested building block with its own checks: yours is put together from the ones your business needs.
- CPI forecastConsensus curve with long-run anchor
- Exchange rate (US dollar)Exchange rate by financial year
- Operating expensesHeadcount build by function
- Corporate costsFixed cost base indexed to CPI
- Working capitalFull working capital
- Income taxCorporate rate with tax losses
- Corporate fixed assetsStraight-line over remaining life
- DebtAmortising term loan
- Dividends and distributionsPayout of net profit
- Discounted cash flow valuationDCF on free cash flow to the firm
- Multiples valuationEV / EBITDA multiple
- LeasesLease register
- Circulation and subscriptionsDigital subscribers × ARPU
- Content and editorial costsEditorial headcount
- Returns and the refund liabilityReturns rate on shipmentsBooks sold on sale-or-return, the returns expected, and the refund liability and returned-stock asset they create.
- Subsidiary rights incomePercentage of salesTranslation, audio, serial, film and TV rights licensed to others, and the author's share.
- Education adoptions and digital licencesAdoption cycleEducational titles sold through curriculum adoption cycles and per-student digital licences.
The numbers it tracks.
- 01net sales
- 02returns rate
- 03backlist share
- 04royalty cost
- 05unearned advances
- 06inventory provision
- 07gross margin
- 08EBITDA margin
More in film, music, publishing and broadcasting.
- Film and TV production company financial model
- Streaming service financial model
- Record label and music publisher financial model
- Music royalty investor financial model
- Radio broadcaster financial model
- Outdoor advertising company financial model
Looking for a book publisher financial model template? Ours arrives built for your business, with your figures in it.
See a finished model, sheet by sheetThe sample is built on illustrative figures and describes no real business. Models are calculations prepared from the information you provide. They are not financial advice and must be independently verified. See our terms.