Indigenous corporation financial model, built free.
A three-statement Excel model for an indigenous land council or corporation, built from your own figures and checked to balance.
- Free account
- No card
- Usually ready within the hour
We use generative AI in parts of our process, so mistakes can occur. Every model should be checked by a person before it is relied on. Read more
A land council, prescribed body corporate or Aboriginal and Torres Strait Islander corporation (or its benefits trust) earning royalty and agreement income from projects on its country, leasing and investment income and government grants, and applying it to member distributions, community programs and a future fund.
In short
- 01
Three linked statements
Income statement, balance sheet and cash flow, linked in every period.
- 02
Valued two ways
Discounted cash flow and trading multiples, side by side.
- 03
Monthly to annual
Monthly, quarterly, half-yearly or annual periods, for up to 30 years.
- 04
Checked every period
A Checks sheet shows the balance sheet balances and the cash reconciles.
The sample, as Excel draws it.
Built by the same system and checks as yours, on illustrative figures: every sheet as Excel draws it, or live.
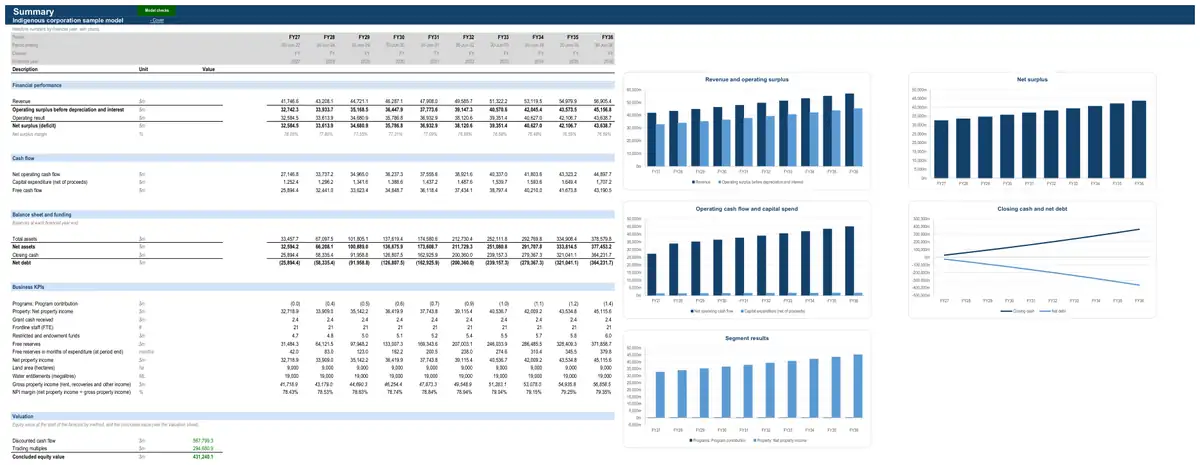
Illustrative figures: the sample describes no real business. The live preview shows values; your model’s Excel file has every formula.
How the model works for an indigenous corporation.
- How it earns revenue3 formulasGrants and restricted funding · All programsClosing unspent grantsOpening unspent grantsGrant cash receivedGrant revenueUnspent funds refunded at acquittalRental income · All propertiesGross rental incomeLettable units or bedsMarket rent per unit per weekWeeks let per yearOccupancy (market-let units)share of the yearRevenue (top-down) · Across the businessRevenueUnits soldAverage price
- What drives its costs3 formulasProgram delivery costs · All programsFrontline staff costsSalaries at award ratesOn-costsProgram delivery costs · All programsProgram delivery costsFrontline staff costsBrokerage and client supportProgram operating costsProperty operating costs · All propertiesProperty operating costsLand area in sqm (hectares × 10000)from property registerOperating cost rateshare of the year
- What it invests in3 formulasCorporate fixed assetsCapital expenditureRevenuefrom statementsCapex as % of revenueAdditional planned capexCorporate fixed assetsDepreciationDepreciation of the opening asset baseDepreciation of new capexCorporate fixed assetsClosing net book valueOpening net book valueCapital expenditureDepreciation
- How profit becomes cash3 formulasWorking capitalTrade receivablesRevenuefrom statementsDebtor daysDays in periodWorking capitalInventoryDirect costs (positive)from statementsInventory daysDays in periodWorking capitalTrade payablesCash operating costs (positive)from statementsCreditor daysDays in period
14 parts, each one tested.
Every part is a tested building block with its own checks: yours is put together from the ones your business needs.
- CPI forecastConsensus curve with long-run anchor
- Revenue (top-down)Price × volume
- Corporate costsFixed cost base indexed to CPI
- Working capitalFull working capital
- Corporate fixed assetsStraight-line over remaining life
- Discounted cash flow valuationDCF on free cash flow to the firm
- Multiples valuationEV / EBITDA multiple
- Reserves policy and restricted fundsFund roll-forwardFund balances by class — restricted, endowment, designated and general (free) reserves — and whether free reserves meet the reserves policy target.
- Grants and restricted fundingDeferred until deliveredGovernment and philanthropic grants funding a program — recognised under AASB 15 where the agreement is enforceable with sufficiently specific performance obligations (deferred until delivered), otherwise on receipt under AASB 1058 — with unspent funds refunded or rolled over on acquittal.
- Program delivery costsCaseload × staffing ratio × award ratesDirect cost of delivering a program — frontline staff under the relevant award, client support and brokerage, program premises and travel.
- Property registerFarm register (hectares, water and improvements)
- Rental incomeUnits × weekly rent × occupancy
- Property operating costsOperating costs per sqm
- Net property income
The numbers it tracks.
- 01agreement income by project
- 02sustainable distribution level
- 03distributions to members
- 04future fund value
- 05program spend
- 06grant dependency
What it is used for.
- Budget and rolling forecastGuide · Cash flow forecast
- Operating forecastGuide · Financial projections
- ValuationGuide · DCF valuation model
- Scenarios and sensitivities
- Closed-end fund, syndicate or trust
More in not-for-profits, clubs and member organisations.
- Charity financial model
- Community housing provider financial model
- Licensed club financial model
- Sporting club financial model
- Industry association financial model
- Co-operative financial model
- Foundation and endowment financial model
- Religious organisation financial model
Looking for an indigenous corporation financial model template? Ours arrives built for your business, with your figures in it.
See a finished model, sheet by sheetThe sample is built on illustrative figures and describes no real business. Models are calculations prepared from the information you provide. They are not financial advice and must be independently verified. See our terms.