Farmland investor financial model, built free.
A three-statement Excel model for a farmland and water investor, built from your own figures and checked to balance.
- Free account
- No card
- Usually ready within the hour
We use generative AI in parts of our process, so mistakes can occur. Every model should be checked by a person before it is relied on. Read more
Owns farmland, orchards, infrastructure and water entitlements and leases them to farm operators, earning rent and water income plus growth in land and water values.
In short
- 01
Three linked statements
Income statement, balance sheet and cash flow, linked in every period.
- 02
Valued two ways
Discounted cash flow and net asset value, side by side.
- 03
Monthly to annual
Monthly, quarterly, half-yearly or annual periods, for up to 30 years.
- 04
Checked every period
A Checks sheet shows the balance sheet balances and the cash reconciles.
The sample, as Excel draws it.
Built by the same system and checks as yours: its structure and its inputs, ready for your own figures.
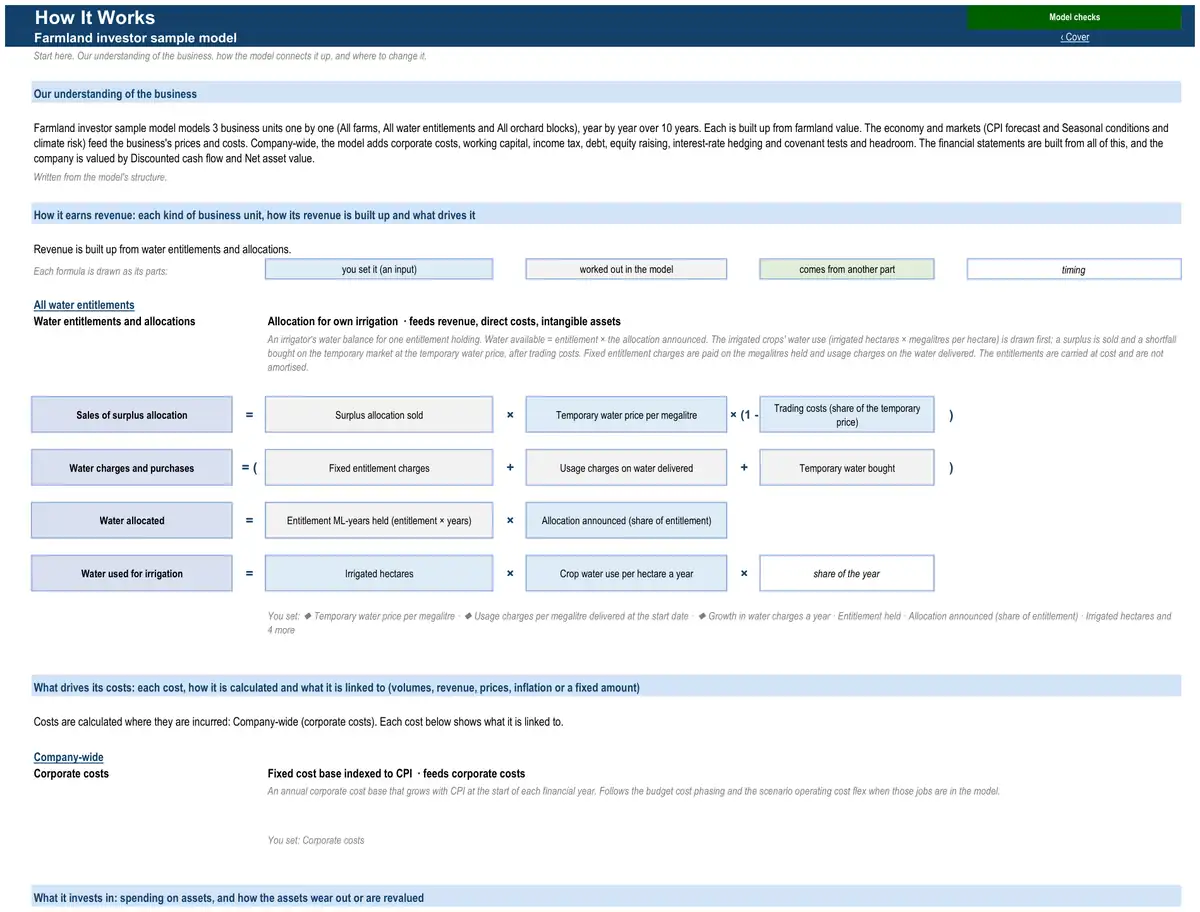
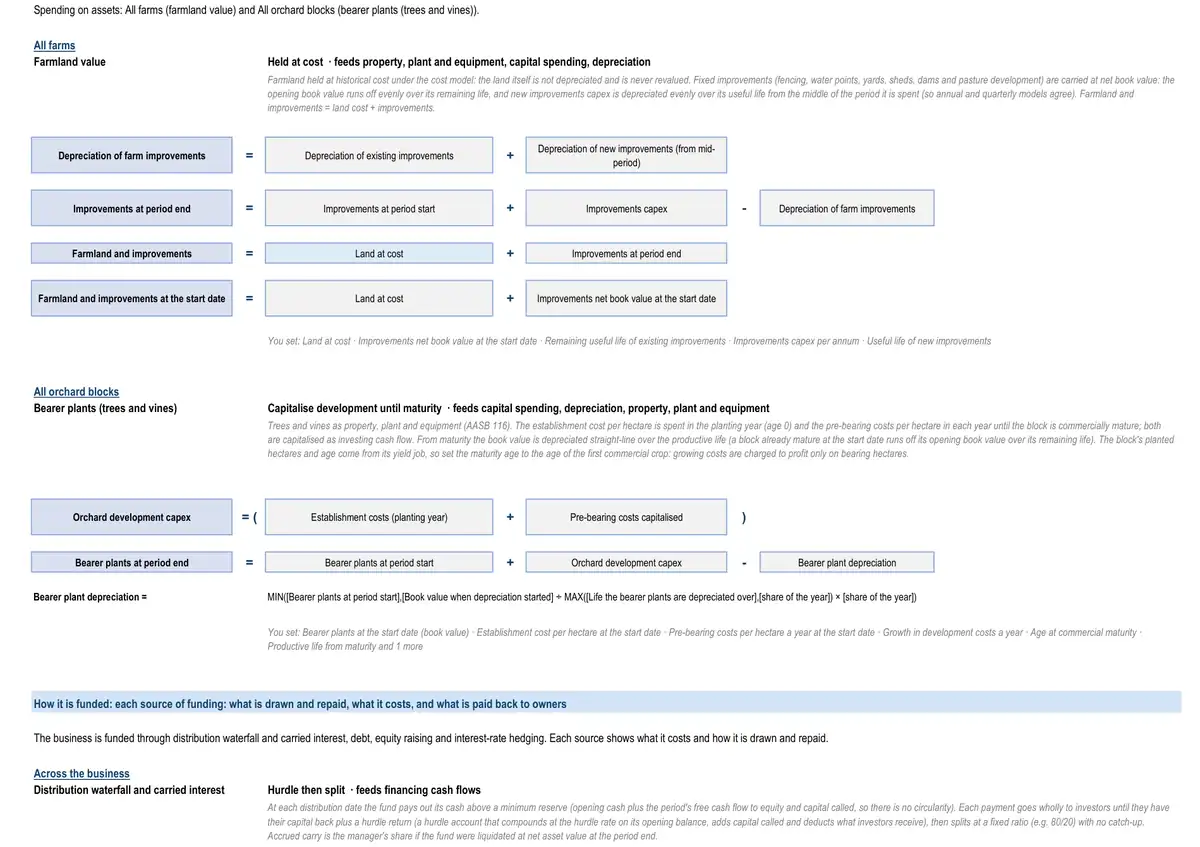
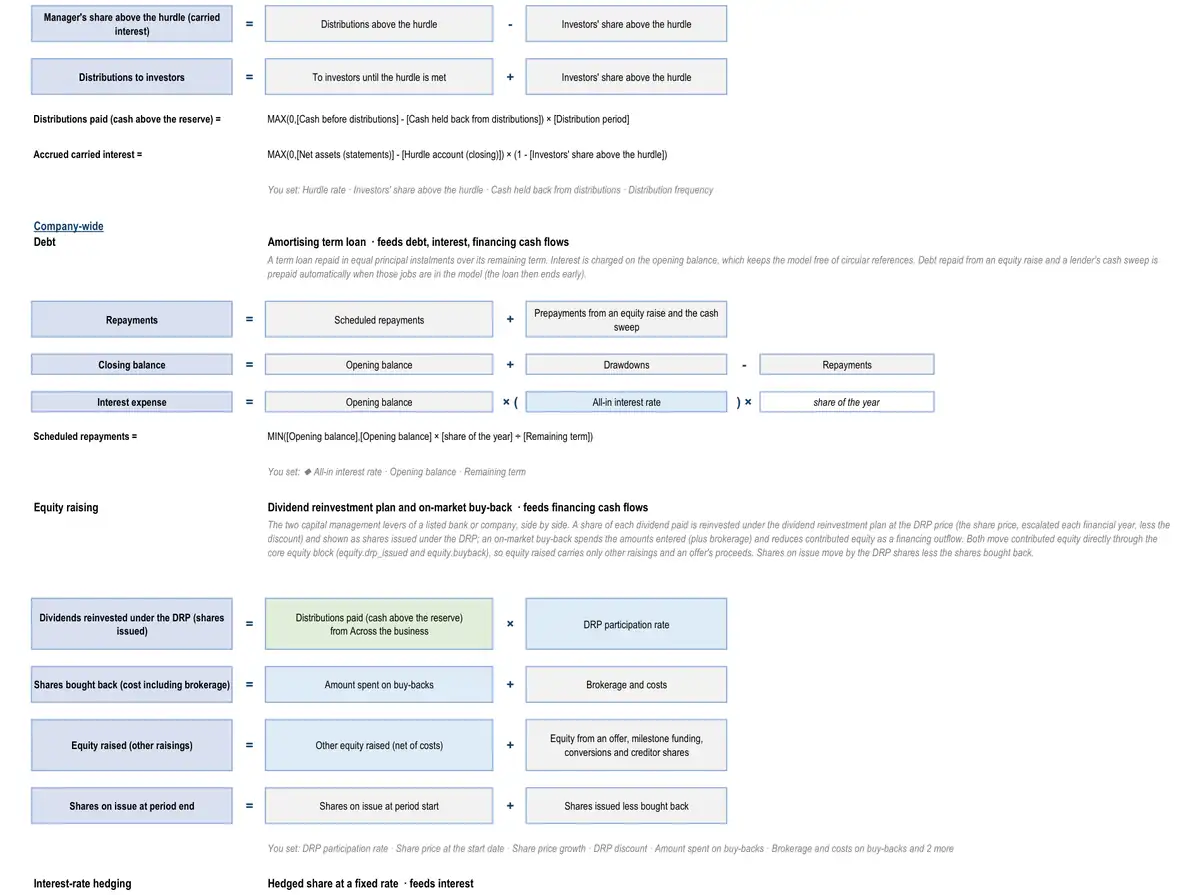
The sample describes no real business. Yours is calibrated to your own figures, so its results are your business’s.
How the model works for a farmland investor.
- How it earns revenue3 formulasWater entitlements and allocations · All water entitlementsSales of surplus allocationSurplus allocation soldTemporary water price per megalitreTrading costs (share of the temporary price)Water entitlements and allocations · All water entitlementsWater charges and purchasesFixed entitlement chargesUsage charges on water deliveredTemporary water boughtWater entitlements and allocations · All water entitlementsWater allocatedEntitlement ML-years held (entitlement × years)Allocation announced (share of entitlement)
- What drives its costs1 partsCorporate costs
- What it invests in3 formulasFarmland value · All farmsDepreciation of farm improvementsDepreciation of existing improvementsDepreciation of new improvements (from mid-period)Farmland value · All farmsImprovements at period endImprovements at period startImprovements capexDepreciation of farm improvementsFarmland value · All farmsFarmland and improvementsLand at costImprovements at period end
- How it is funded3 formulasDistribution waterfall and carried interest · Across the businessManager's share above the hurdle (carried interest)Distributions above the hurdleInvestors' share above the hurdleDistribution waterfall and carried interest · Across the businessDistributions to investorsTo investors until the hurdle is metInvestors' share above the hurdleDebtRepaymentsScheduled repaymentsPrepayments from an equity raise and the cash sweep
- How profit becomes cash3 formulasWorking capitalTrade receivablesRevenuefrom statementsDebtor daysDays in periodWorking capitalInventoryDirect costs (positive)from statementsInventory daysDays in periodWorking capitalTrade payablesCash operating costs (positive)from statementsCreditor daysDays in period
22 parts, each one tested.
Every part is a tested building block with its own checks: yours is put together from the ones your business needs.
- CPI forecastConsensus curve with long-run anchor
- Corporate costsFixed cost base indexed to CPI
- Working capitalFull working capital
- Income taxCorporate rate with tax losses
- DebtAmortising term loan
- Equity raisingDividend reinvestment plan and on-market buy-back
- Discounted cash flow valuationDCF on free cash flow to the firm
- Net asset valueBook net asset value
- Interest-rate hedgingHedged share at a fixed rate
- Purchase price and acquisition costsAgreed price plus costs
- Hold-period cash flowsAsset-level NOI less capex
- Exit value and exit costsTerminal capitalisation rate
- Investment returnsIRR, equity multiple and cash-on-cash
- Key-metric summaryLast-twelve-month and run-rate metrics
- Covenant tests and headroomLVR, gearing and ICR for property
- Distribution waterfall and carried interestHurdle then split
- Discount rate (WACC)CAPM at target gearing
- Seasonal conditions and climate riskLong-run average seasonA season factor that scales yields, carrying capacity, receivals, input demand (or, for ski resorts, snow and skier visits) for drought, average and good years.
- Farmland valueHeld at costValue of farmland and fixed improvements — held at cost, revalued, or at fair value for leased-out farms.
- Water entitlements and allocationsAllocation for own irrigationWater available from each entitlement holding — its allocation, use, trade and charges — and its carrying value.
- Orchard and vineyard yieldBearing hectares × mature yieldBearing hectares and tonnes harvested from each block as trees or vines mature, alternate-bear and age.
- Bearer plants (trees and vines)Capitalise development until maturityTrees and vines are property, plant and equipment (AASB 116) — development costs are capitalised until commercial production, then depreciated over the productive life.
The numbers it tracks.
- 01adjusted FFO per unit
- 02NAV per unit
- 03gearing
- 04WALE
- 05lease yield on value
- 06water value per ML
What it is used for.
- Operating forecastGuide · Financial projections
- ValuationGuide · DCF valuation model
- Lending and credit analysisGuide · Three-statement model
- Asset acquisition
- Closed-end fund, syndicate or trust
More in farmland, agribusiness and rural services.
- Farm management company financial model
- Agricultural contractor financial model
- Rural services agency financial model
- Rural supplies distributor financial model
- Farm machinery dealer financial model
- Agtech company financial model
- Grain storage and handling financial model
- Grain trader financial model
Looking for a farmland investor financial model template? Ours arrives built for your business, with your figures in it.
See a finished model, sheet by sheetThe sample is built on illustrative figures and describes no real business. Models are calculations prepared from the information you provide. They are not financial advice and must be independently verified. See our terms.