Beauty brand financial model, built free.
A three-statement Excel model for a beauty and personal-care brand, built from your own figures and checked to balance.
- Free account
- No card
- Usually ready within the hour
We use generative AI in parts of our process, so mistakes can occur. Every model should be checked by a person before it is relied on. Read more
Develops skincare, cosmetics, fragrance, hair, oral-care and personal hygiene products, made in-house or by contract manufacturers, and sells them through pharmacies, supermarkets, department stores, beauty retailers, travel retail and its own websites, with high gross margins funding heavy advertising and influencer spend.
In short
- 01
Three linked statements
Income statement, balance sheet and cash flow, linked in every period.
- 02
Valued two ways
Discounted cash flow and trading multiples, side by side.
- 03
Monthly to annual
Monthly, quarterly, half-yearly or annual periods, for up to 30 years.
- 04
Checked every period
A Checks sheet shows the balance sheet balances and the cash reconciles.
The sample, as Excel draws it.
Built by the same system and checks as yours, on illustrative figures: every sheet as Excel draws it, or live.
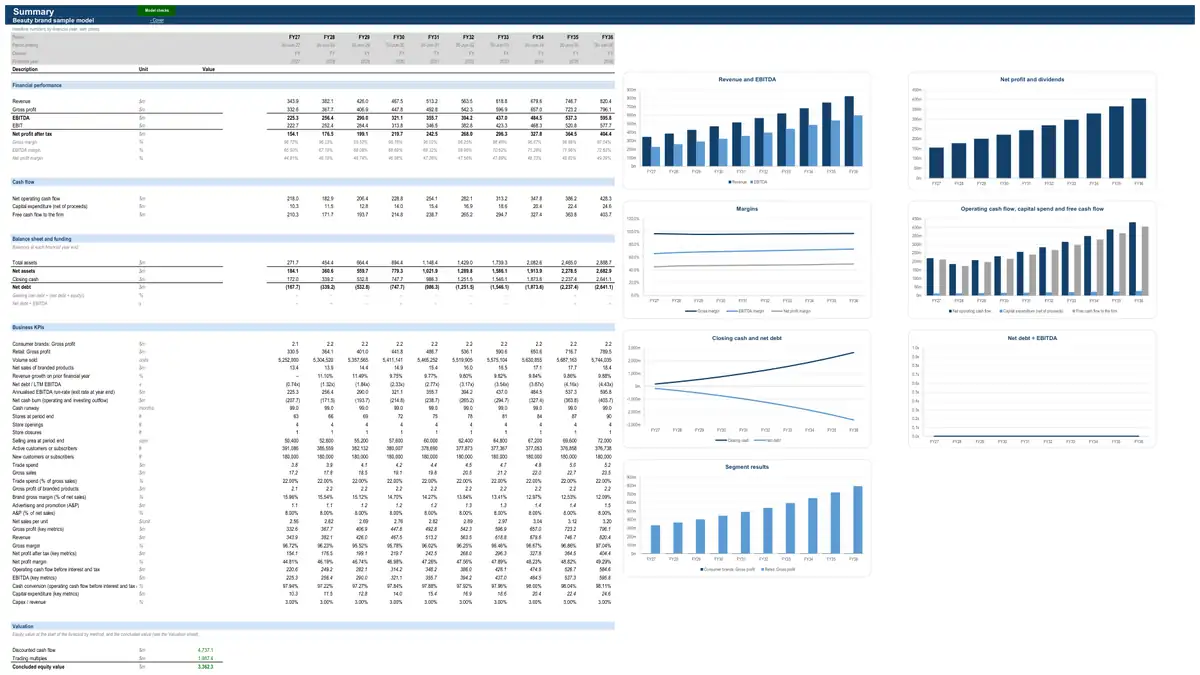
Illustrative figures: the sample describes no real business. The live preview shows values; your model’s Excel file has every formula.
How the model works for a beauty brand.
- How it earns revenue3 formulasProduct-range sales · All product rangesGross salesVolume soldPrice to retailer per unitTrade spend (gross to net) · All product rangesTrade spendGross salesfrom product-range salesTrade spend (% of gross sales)Sales · All store formatsOnline salesOrdersAverage order value
- What drives its costs3 formulasProduct cost of goods and gross profit · All product rangesStandard cost per unitMaterials and ingredientsPackagingConversion labourPlant overheadInbound freightProduct cost of goods and gross profit · All product rangesCost of goods soldVolume soldfrom product-range salesStandard cost per unitProduct cost of goods and gross profit · All product rangesNet salesGross sales (product-range sales)from product-range salesTrade spend (trade spend (gross to net))from gross to net
- What it invests in3 formulasCorporate fixed assetsCapital expenditureRevenuefrom statementsCapex as % of revenueAdditional planned capexCorporate fixed assetsDepreciationDepreciation of the opening asset baseDepreciation of new capexCorporate fixed assetsClosing net book valueOpening net book valueCapital expenditureDepreciation
- How it is funded3 formulasDebtRepaymentsScheduled repaymentsPrepayments from an equity raise and the cash sweepDebtClosing balanceOpening balanceDrawdownsRepaymentsDebtInterest expenseOpening balanceAll-in interest rateshare of the year
- How profit becomes cash3 formulasWorking capitalTrade receivablesRevenuefrom statementsDebtor daysDays in periodWorking capitalInventoryDirect costs (positive)from statementsInventory daysDays in periodWorking capitalTrade payablesCash operating costs (positive)from statementsCreditor daysDays in period
28 parts, each one tested.
Every part is a tested building block with its own checks: yours is put together from the ones your business needs.
- CPI forecastConsensus curve with long-run anchor
- Exchange rate (US dollar)Exchange rate by financial year
- Operating expensesHeadcount build by function
- Corporate costsFixed cost base indexed to CPI
- Working capitalFull working capital
- Income taxCorporate rate with tax losses
- Corporate fixed assetsStraight-line over remaining life
- DebtAmortising term loan
- Equity raisingDistribution reinvestment plan
- Discounted cash flow valuationDCF on free cash flow to the firm
- Multiples valuationEV / EBITDA multiple
- Key-metric summaryLast-twelve-month and run-rate metrics
- Covenant tests and headroomLVR, gearing and ICR for property
- SynergiesRun-rate synergies with phasing
- Sources and uses of fundsBalanced sources and uses
- Discount rate (WACC)CAPM at target gearing
- Burn and runwayRunway to the forecast cash-out date
- InventoryStock per store plus DC stockStock held in stores, distribution centres and in transit, and the cash it ties up.
- Distribution and logisticsLogistics % of salesDistribution-centre, warehousing and outbound freight costs of moving goods to stores, customers or retail accounts.
- Product-range salesDistribution × rate of saleGross sales of a brand, category or SKU family to retailers, wholesale accounts and export markets.
- Trade spend (gross to net)Trade spend % of gross salesPayments and discounts to retail customers — promotional allowances, rebates, listing fees and co-operative marketing — deducted from gross sales to reach net revenue.
- Product cost of goods and gross profitUnit cost buildCost of making or buying each product range — materials, packaging, conversion and inbound freight.
- Advertising and promotion (A&P)A&P % of net salesBrand investment in media, sponsorship and consumer promotion (separate from trade spend paid to retailers).
- Store networkScheduled openings and closuresStores trading in each period — openings, closures and selling area — which every per-store driver multiplies.
- SalesOnline sales from active customers × orders × order valueSales of the format — stores, restaurants, cafés or an online channel — the revenue base of every retailer.
- Store and channel operating costsPer-store wages, rent and other costsCosts of running the format — store wages, rent and occupancy, running costs, or an online channel's fulfilment and platform costs (rent here is the pre-AASB 16 cash view).
- Marketing and customer acquisitionNew customers × CAC plus retentionSpend on acquiring and retaining customers — media, catalogues, paid search and social, affiliates and CRM.
- Customers and subscribersAcquisition and churn roll-forwardActive customers or subscribers of an online format — how many are acquired, retained and lost — used by customer-based sales and acquisition-cost methods.
The numbers it tracks.
- 01net sales by channel
- 02DTC share
- 03gross margin %
- 04A&P % of net sales
- 05EBIT margin
- 06customer acquisition cost
What it is used for.
- Operating forecastGuide · Financial projections
- ValuationGuide · DCF valuation model
- Lending and credit analysisGuide · Three-statement model
- Merger or acquisition (strategic)Guide · Financial modelling services
- Equity capital raisingGuide · Startup financial model
- Startup and venture fundingGuide · Startup financial model
More in consumer brands.
- FMCG brand financial model
- Fashion brand financial model
- Luxury goods house financial model
- Household products brand financial model
- Consumer electronics brand financial model
- Leisure products brand financial model
- Private-label manufacturer financial model
- Brand licensing company financial model
Looking for a beauty brand financial model template? Ours arrives built for your business, with your figures in it.
Running a small business? Read what goes into a small business financial model.
See a finished model, sheet by sheetThe sample is built on illustrative figures and describes no real business. Models are calculations prepared from the information you provide. They are not financial advice and must be independently verified. See our terms.