Brand licensing company financial model, built free.
A three-statement Excel model for a brand licensor and IP owner, built from your own figures and checked to balance.
- Free account
- No card
- Usually ready within the hour
We use generative AI in parts of our process, so mistakes can occur. Every model should be checked by a person before it is relied on. Read more
Owns consumer brands, characters or formulations and licenses them to manufacturers, distributors and retailers by category and territory, earning royalties with guaranteed minimums and growing by acquiring more brands; costs are brand management and marketing only.
In short
- 01
Three linked statements
Income statement, balance sheet and cash flow, linked in every period.
- 02
Valued two ways
Discounted cash flow and trading multiples, side by side.
- 03
Monthly to annual
Monthly, quarterly, half-yearly or annual periods, for up to 30 years.
- 04
Checked every period
A Checks sheet shows the balance sheet balances and the cash reconciles.
The sample, as Excel draws it.
Built by the same system and checks as yours, on illustrative figures: every sheet as Excel draws it, or live.
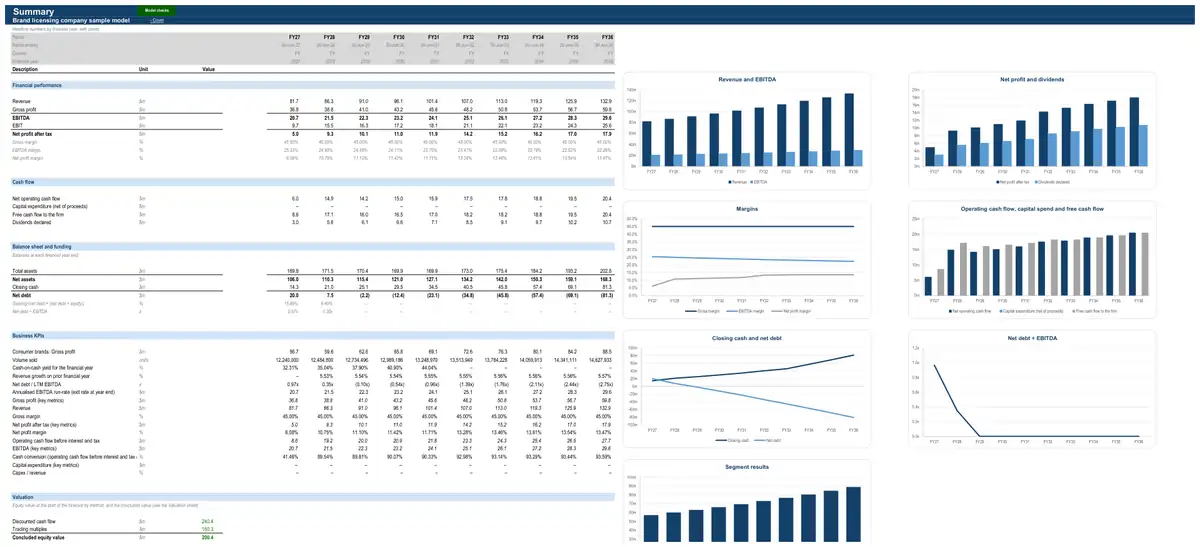
Illustrative figures: the sample describes no real business. The live preview shows values; your model’s Excel file has every formula.
How the model works for a brand licensing company.
- How it earns revenue3 formulasProduct-range sales · All product rangesGross salesVolume soldList price per unitProduct-range sales · All product rangesVolume soldAnnual volume run-rateshare of the yearSeasonal sales indexRevenue (top-down) · Across the businessRevenueUnits soldAverage price
- What drives its costs3 formulasAdvertising and promotion (A&P) · All product rangesAdvertising and promotionNet salesA&P (% of net sales)Direct costs (top-down) · Across the businessCost of salesRevenuefrom statementsGross marginOperating expenses · Across the businessTotal FTEsOperations and deliverySales and marketingTechnologyFinance, HR and administration
- What it invests in3 formulasPurchase price allocation · Valuation and analysisIdentifiable net assets at fair valueTarget book net assets at completionTarget's existing goodwill written offAdd acquired intangibles at fair valueLess deferred tax on the intangiblesPurchase price allocation · Valuation and analysisAmortisation of acquired intangiblesCustomer relationshipsBrand namesTechnologyOrder backlogPurchase price allocation · Valuation and analysisClosing balanceOpening balanceAmortisation of acquired intangibles
- How it is funded3 formulasDebtRepaymentsScheduled repaymentsPrepayments from an equity raise and the cash sweepDebtClosing balanceOpening balanceDrawdownsRepaymentsDebtInterest expenseOpening balanceAll-in interest rateshare of the year
- How profit becomes cash3 formulasWorking capitalTrade receivablesRevenuefrom statementsDebtor daysDays in periodWorking capitalInventoryDirect costs (positive)from statementsInventory daysDays in periodWorking capitalTrade payablesCash operating costs (positive)from statementsCreditor daysDays in period
23 parts, each one tested.
Every part is a tested building block with its own checks: yours is put together from the ones your business needs.
- CPI forecastConsensus curve with long-run anchor
- Exchange rate (US dollar)Exchange rate by financial year
- Revenue (top-down)Price × volume
- Direct costs (top-down)Gross margin %
- Operating expensesHeadcount build by function
- Corporate costsFixed cost base indexed to CPI
- Working capitalFull working capital
- Income taxCorporate rate with tax losses
- DebtAmortising term loan
- Equity raisingDistribution reinvestment plan
- Dividends and distributionsPayout of net profit
- Discounted cash flow valuationDCF on free cash flow to the firm
- Multiples valuationEV / EBITDA multiple
- Purchase price and acquisition costsAgreed price plus costs
- Hold-period cash flowsAsset-level NOI less capex
- Exit value and exit costsTerminal capitalisation rate
- Investment returnsIRR, equity multiple and cash-on-cash
- Key-metric summaryLast-twelve-month and run-rate metrics
- Covenant tests and headroomLVR, gearing and ICR for property
- Purchase price allocationAcquired intangibles with deferred tax
- Discount rate (WACC)CAPM at target gearing
- Product-range salesVolume × priceGross sales of a brand, category or SKU family to retailers, wholesale accounts and export markets.
- Advertising and promotion (A&P)A&P % of net salesBrand investment in media, sponsorship and consumer promotion (separate from trade spend paid to retailers).
The numbers it tracks.
- 01licensee retail sales
- 02royalty income
- 03guaranteed minimums
- 04royalty rate
- 05EBITDA margin
- 06brand acquisition multiple
What it is used for.
- Operating forecastGuide · Financial projections
- ValuationGuide · DCF valuation model
- Lending and credit analysisGuide · Three-statement model
- Asset acquisition
More in consumer brands.
- FMCG brand financial model
- Fashion brand financial model
- Luxury goods house financial model
- Beauty brand financial model
- Household products brand financial model
- Consumer electronics brand financial model
- Leisure products brand financial model
- Private-label manufacturer financial model
Looking for a brand licensing company financial model template? Ours arrives built for your business, with your figures in it.
Running a small business? Read what goes into a small business financial model.
See a finished model, sheet by sheetThe sample is built on illustrative figures and describes no real business. Models are calculations prepared from the information you provide. They are not financial advice and must be independently verified. See our terms.