Oil and gas producer financial model, built free.
A three-statement Excel model for an oil and gas producer (exploration and production), built from your own figures and checked to balance.
- Free account
- No card
- Usually ready within the hour
We use generative AI in parts of our process, so mistakes can occur. Every model should be checked by a person before it is relied on. Read more
Finds, develops and produces oil and gas — conventional fields, shale and tight oil, coal-seam gas — from interests it holds, selling at benchmark-linked or contracted prices after royalties and resource taxes.
In short
- 01
Three linked statements
Income statement, balance sheet and cash flow, linked in every period.
- 02
Valued two ways
Discounted cash flow and net asset value, side by side.
- 03
Monthly to annual
Monthly, quarterly, half-yearly or annual periods, for up to 30 years.
- 04
Checked every period
A Checks sheet shows the balance sheet balances and the cash reconciles.
The sample, as Excel draws it.
Built by the same system and checks as yours, on illustrative figures: every sheet as Excel draws it, or live.
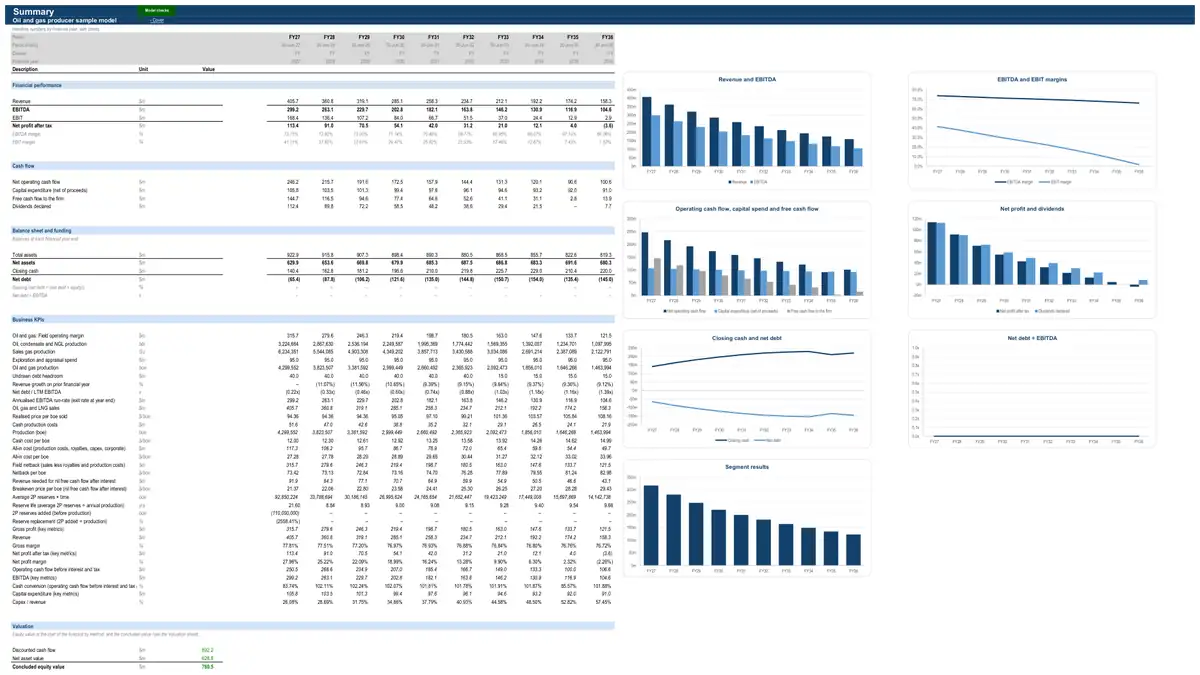
Illustrative figures: the sample describes no real business. The live preview shows values; your model’s Excel file has every formula.
How the model works for an oil and gas producer.
- How it earns revenue1 formulaOil, gas and LNG sales · All oil and gas assetsOil, gas and LNG salesOil, condensate and NGL salesGas sales
- What drives its costs3 formulasRoyalties and resource taxes · All oil and gas assetsRoyaltiesWellhead valueRoyalty rateProduction costs · All oil and gas assetsProduction costsNet productionfrom productionProduction cost per boeExploration programme and risked resources · Across the businessWell costs capitalisedWell costsShare of well costs capitalised
- What it invests in3 formulasCapex, depletion and exploration · All oil and gas assetsDevelopment and sustaining capexSustaining capexGrowth capexCapex, depletion and exploration · All oil and gas assetsDepletion (units of production)Opening net book valueDevelopment and sustaining capexShare of the reserves producedCapex, depletion and exploration · All oil and gas assetsClosing net book valueOpening net book valueDevelopment and sustaining capexDepletion (units of production)
- How it is funded3 formulasDecommissioning and restoration provisions · Across the businessUnwinding of discount (non-cash finance cost)Unwinding of discountUnwinding of discountUnwinding of discountDecommissioning and restoration provisions · Across the businessDecommissioning and restoration provisionClosing provisionClosing provisionClosing provisionDecommissioning and restoration provisions · Across the businessOpening decommissioning provisionOpening provision (present value)from present valueSecond obligation opening provisionThird obligation opening provision
- How profit becomes cash3 formulasWorking capitalTrade receivablesRevenuefrom statementsDebtor daysDays in periodWorking capitalInventoryDirect costs (positive)from statementsInventory daysDays in periodWorking capitalTrade payablesCash operating costs (positive)from statementsCreditor daysDays in period
23 parts, each one tested.
Every part is a tested building block with its own checks: yours is put together from the ones your business needs.
- CPI forecastConsensus curve with long-run anchor
- Exchange rate (US dollar)Exchange rate by financial year
- Corporate costsFixed cost base indexed to CPI
- Working capitalDays-based working capital
- Income taxCorporate rate with tax losses
- DebtFacility register with limits and refinancing
- Equity raisingDistribution reinvestment plan
- Dividends and distributionsPayout of free cash flow to equity
- Discounted cash flow valuationDCF on free cash flow to the firm
- Net asset valueBook net asset value
- Exploration programme and risked resourcesWells and seismic budgetExploration and appraisal spend, farm-outs, and the risked value of prospects and discovered but undeveloped resources.
- Decommissioning and restoration provisionsPresent value with accretionProvisions to remove generation assets, abandon wells and restore sites — recognition, unwinding and spend.
- Energy and utility KPIsUpstream unit metricsThe ratios investors and lenders use to judge energy and utility businesses.
- Interest-rate hedgingHedged share at a fixed rate
- Key-metric summaryLast-twelve-month and run-rate metrics
- Borrowing base and security coverReceivables and inventory borrowing base
- Discount rate (WACC)CAPM at target gearing
- Field and project registerInterest, reserves and book valueWorking interest, reserves and carrying value of each field or LNG project.
- ProductionExponential declineOil, gas and LNG volumes produced each period (net to the company's interest).
- Oil, gas and LNG salesBenchmark × differential by productRealised prices × volumes for oil, condensate, gas and LNG.
- Royalties and resource taxesRoyalty on wellhead valueGovernment and private royalties, production sharing and petroleum resource taxes.
- Production costsCost per boeLifting, processing, transport and liquefaction costs.
- Capex, depletion and explorationUnits-of-production depletionDevelopment and sustaining capex, exploration spend, and depletion of oil and gas properties.
The numbers it tracks.
- 01production (boe per day)
- 02realised price
- 03cash cost per boe
- 04netback
- 05reserve life
- 06NAV per share
What it is used for.
- Operating forecastGuide · Financial projections
- Budget and rolling forecastGuide · Cash flow forecast
- ValuationGuide · DCF valuation model
- Lending and credit analysisGuide · Three-statement model
- Equity capital raisingGuide · Startup financial model
- Merger or acquisition (strategic)Guide · Financial modelling services
- Project financeGuide · Financial modelling services
- Scenarios and sensitivities
- Asset acquisition
More in oil and gas.
- Oil and gas explorer financial model
- Integrated oil and gas company financial model
- LNG producer financial model
- Oil sands producer financial model
- Oil and gas royalty owner financial model
- Oilfield services company financial model
- Drilling contractor financial model
- Midstream pipeline operator financial model
- LNG import terminal financial model
- Oil refiner financial model
- Fuel distributor financial model
- LPG distributor financial model
Looking for an oil and gas producer financial model template? Ours arrives built for your business, with your figures in it.
See a finished model, sheet by sheetThe sample is built on illustrative figures and describes no real business. Models are calculations prepared from the information you provide. They are not financial advice and must be independently verified. See our terms.