Consumer lender financial model, built free.
A three-statement Excel model for a consumer lender and card issuer, built from your own figures and checked to balance.
- Free account
- No card
- Usually ready within the hour
We use generative AI in parts of our process, so mistakes can occur. Every model should be checked by a person before it is relied on. Read more
Non-bank lender of personal loans, credit cards, car loans or small-amount credit to consumers, earning high yields and fees against high credit losses, funded by warehouses, ABS and corporate debt.
In short
- 01
Three linked statements
Income statement, balance sheet and cash flow, linked in every period.
- 02
Valued two ways
Discounted cash flow and trading multiples, side by side.
- 03
Monthly to annual
Monthly, quarterly, half-yearly or annual periods, for up to 30 years.
- 04
Checked every period
A Checks sheet shows the balance sheet balances and the cash reconciles.
The sample, as Excel draws it.
Built by the same system and checks as yours: its structure and its inputs, ready for your own figures.
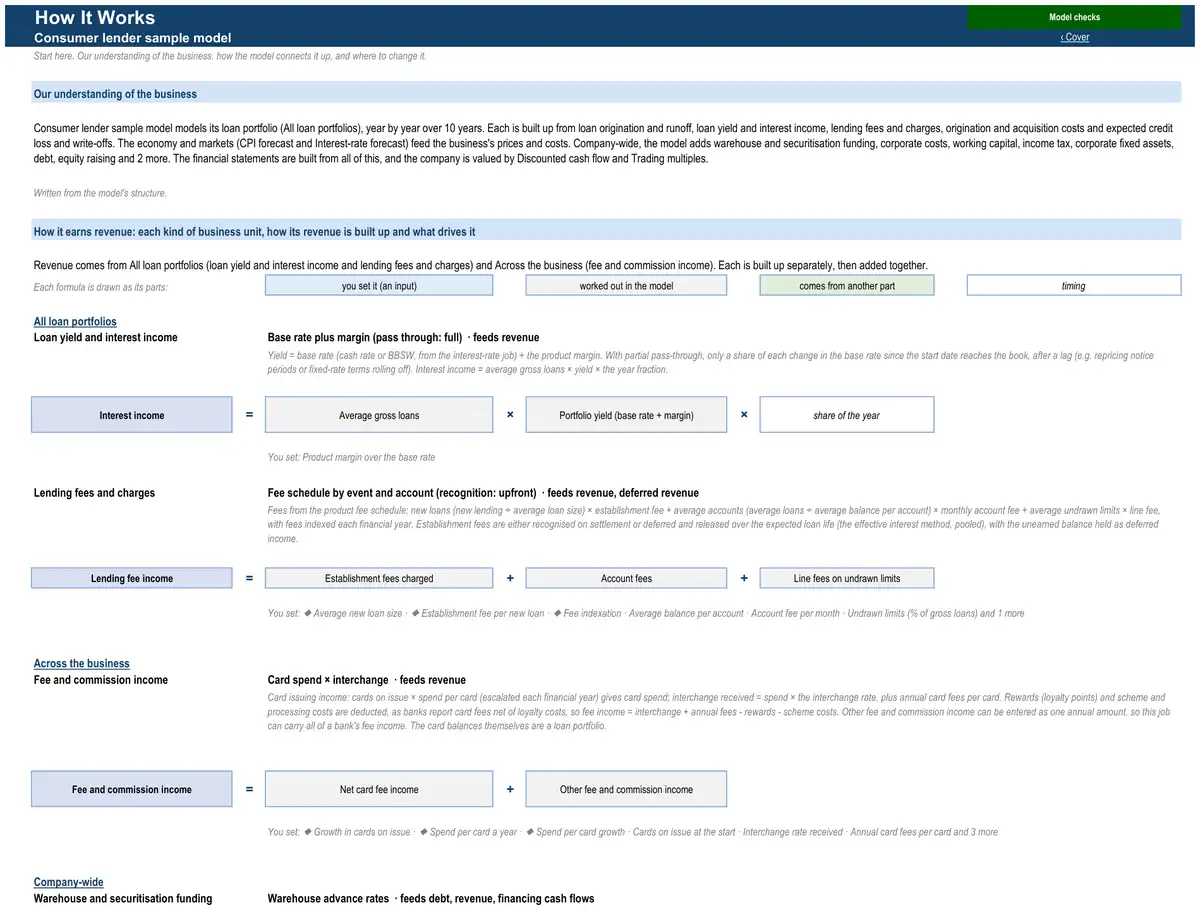
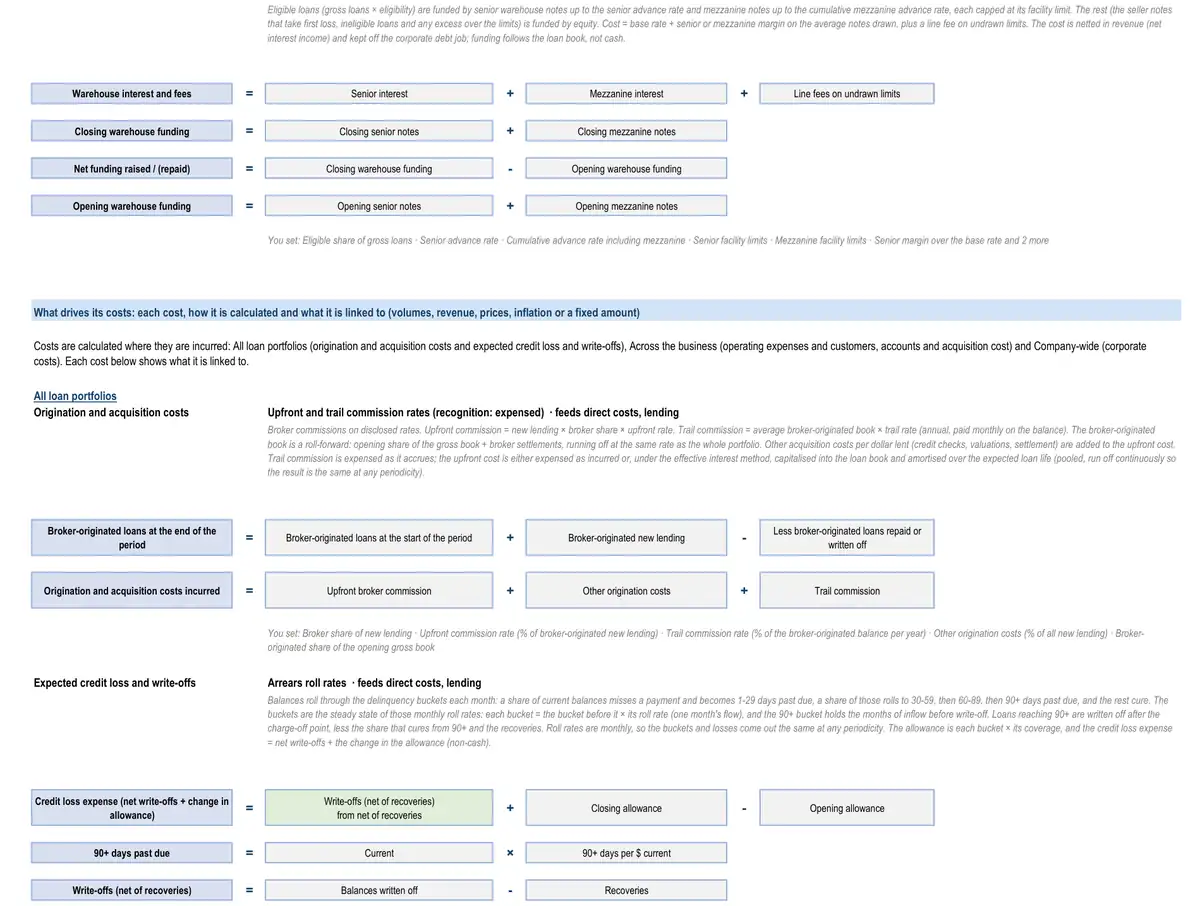
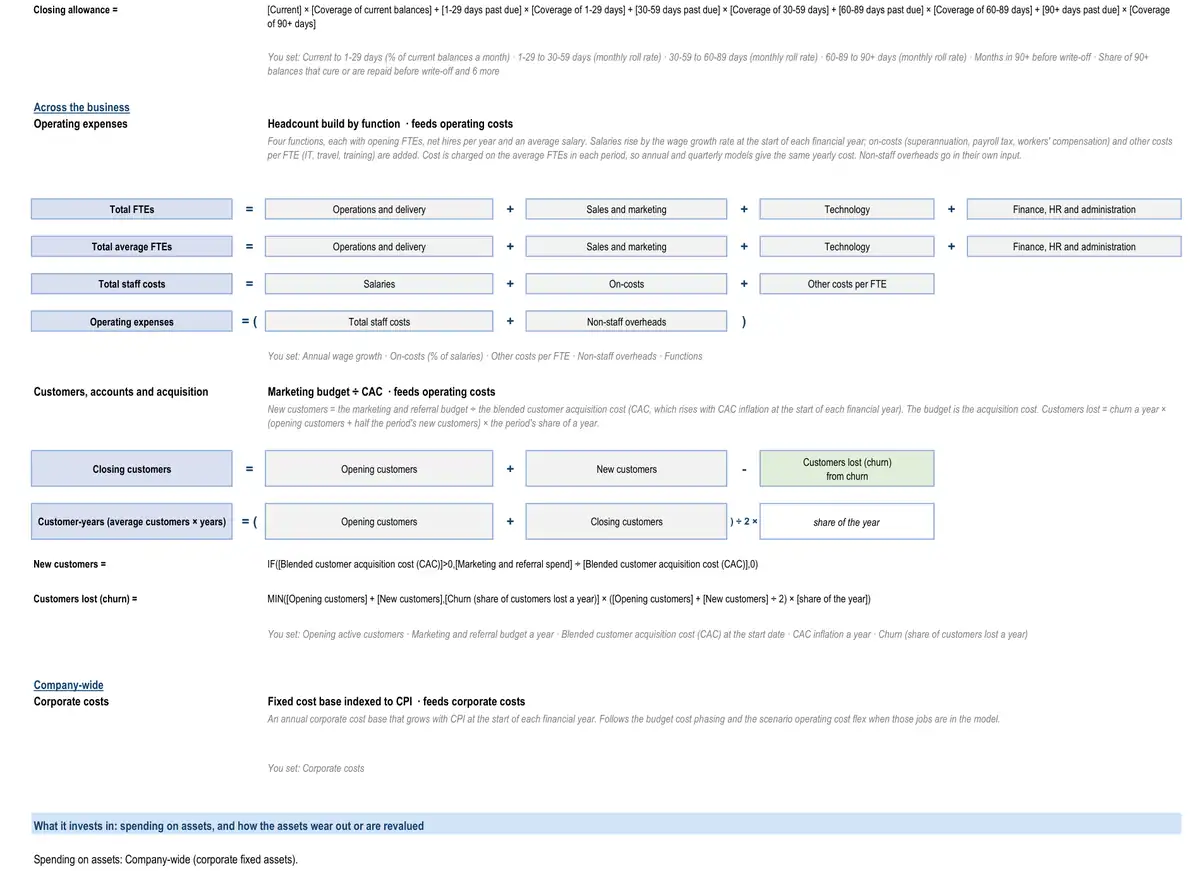
The sample describes no real business. Yours is calibrated to your own figures, so its results are your business’s.
How the model works for a consumer lender.
- How it earns revenue3 formulasLoan yield and interest income · All loan portfoliosInterest incomeAverage gross loansPortfolio yield (base rate + margin)share of the yearLending fees and charges · All loan portfoliosLending fee incomeEstablishment fees chargedAccount feesLine fees on undrawn limitsFee and commission income · Across the businessFee and commission incomeNet card fee incomeOther fee and commission income
- What drives its costs3 formulasOrigination and acquisition costs · All loan portfoliosBroker-originated loans at the end of the periodBroker-originated loans at the start of the periodBroker-originated new lendingLess broker-originated loans repaid or written offOrigination and acquisition costs · All loan portfoliosOrigination and acquisition costs incurredUpfront broker commissionOther origination costsTrail commissionExpected credit loss and write-offs · All loan portfoliosCredit loss expense (net write-offs + change in allowance)Write-offs (net of recoveries)from net of recoveriesClosing allowanceOpening allowance
- What it invests in3 formulasCorporate fixed assetsCapital expenditureRevenuefrom statementsCapex as % of revenueAdditional planned capexCorporate fixed assetsDepreciationDepreciation of the opening asset baseDepreciation of new capexCorporate fixed assetsClosing net book valueOpening net book valueCapital expenditureDepreciation
- How it is funded3 formulasLoan origination and runoff · All loan portfoliosClosing gross loans (limits × utilisation)Total limitsUtilisation (drawn balances ÷ limits)Loan origination and runoff · All loan portfoliosNet loans advanced (new lending less cash repayments)Closing gross loans (limits × utilisation)Opening gross loansWrite-offs (net of recoveries)from expected credit loss and write-offsLoan origination and runoff · All loan portfoliosOpening gross loans (accounts × limit × utilisation)Open accounts at the start dateAverage limit per account at the start dateUtilisation (drawn balances ÷ limits)
- How profit becomes cash3 formulasWorking capitalTrade receivablesRevenuefrom statementsDebtor daysDays in periodWorking capitalInventoryDirect costs (positive)from statementsInventory daysDays in periodWorking capitalTrade payablesCash operating costs (positive)from statementsCreditor daysDays in period
24 parts, each one tested.
Every part is a tested building block with its own checks: yours is put together from the ones your business needs.
- CPI forecastConsensus curve with long-run anchor
- Operating expensesHeadcount build by function
- Corporate costsFixed cost base indexed to CPI
- Working capitalFull working capital
- Income taxCorporate rate with tax losses
- Corporate fixed assetsStraight-line over remaining life
- DebtAmortising term loan
- Equity raisingDistribution reinvestment plan
- Dividends and distributionsPayout of net profit
- Discounted cash flow valuationDCF on free cash flow to the firm
- Multiples valuationEV / EBITDA multiple
- Fee and commission incomeCard spend × interchangeNon-interest income from account, lending, card, trade and wealth fees.
- Customers, accounts and acquisition costMarketing budget ÷ CACActive customers or funded accounts of a digital financial service (neobank, BNPL, broker, crypto or wealth app) and the marketing and onboarding cost of winning them.
- Warehouse and securitisation fundingWarehouse advance ratesNon-bank funding of the loan book through warehouse facilities, term securitisation and whole-loan sales, and its interest cost.
- Lender and bank key metricsNIM bridge by driverNet interest margin, spread, cost-to-income ratio, loss rate and returns for banks and lenders, and their drivers.
- Key-metric summaryLast-twelve-month and run-rate metrics
- Covenant tests and headroomLVR, gearing and ICR for property
- Case selectionStackable stress toggles
- Interest-rate forecastMarket forward curve
- Loan origination and runoffLimits × utilisationGross loans rolled forward from new lending, scheduled repayments, prepayments and write-offs.
- Loan yield and interest incomeBase rate plus marginInterest income earned on each portfolio from its yield, repricing and fees.
- Lending fees and chargesFee schedule by event and accountFee income on a loan portfolio — establishment and application fees, monthly account fees, line and commitment fees on undrawn limits, late and default fees, discount and service fees on invoice finance, and early repayment charges.
- Origination and acquisition costsUpfront and trail commission ratesCosts of winning each loan — broker upfront and trail commissions, dealer incentives, credit bureau, verification, valuation and settlement costs — expensed or deferred into the loan's effective yield.
- Expected credit loss and write-offsArrears roll ratesCredit loss expense, the expected credit loss allowance held against loans, and write-offs.
The numbers it tracks.
- 01receivables
- 02originations
- 03yield
- 04net charge-offs
- 05risk-adjusted margin
- 06cost of funds
- 07cost-to-income ratio
- 08return on equity
What it is used for.
- Operating forecastGuide · Financial projections
- Budget and rolling forecastGuide · Cash flow forecast
- ValuationGuide · DCF valuation model
- Equity capital raisingGuide · Startup financial model
- Lending and credit analysisGuide · Three-statement model
- Scenarios and sensitivities
More in banking and lending.
- Bank financial model
- Credit union financial model
- Neobank financial model
- Non-bank lender financial model
- Buy now pay later provider financial model
- Invoice finance lender financial model
- Equipment and auto finance company financial model
- Mortgage lender financial model
- Mortgage broker financial model
- Mortgage REIT financial model
- Private credit fund financial model
- Pawnbroker and small-amount lender financial model
- Debt collection agency financial model
- Development bank financial model
Looking for a consumer lender financial model template? Ours arrives built for your business, with your figures in it.
See a finished model, sheet by sheetThe sample is built on illustrative figures and describes no real business. Models are calculations prepared from the information you provide. They are not financial advice and must be independently verified. See our terms.