Orchard and vineyard financial model, built free.
A three-statement Excel model for an orchard, nut and vineyard grower, built from your own figures and checked to balance.
- Free account
- No card
- Usually ready within the hour
We use generative AI in parts of our process, so mistakes can occur. Every model should be checked by a person before it is relied on. Read more
Grows tree fruit, nuts, citrus, avocados or wine and table grapes on planted blocks that take years to reach full production, selling the crop domestically, for export or to wineries.
In short
- 01
Three linked statements
Income statement, balance sheet and cash flow, linked in every period.
- 02
Valued two ways
Discounted cash flow and net asset value, side by side.
- 03
Monthly to annual
Monthly, quarterly, half-yearly or annual periods, for up to 30 years.
- 04
Checked every period
A Checks sheet shows the balance sheet balances and the cash reconciles.
The sample, as Excel draws it.
Built by the same system and checks as yours: its structure and its inputs, ready for your own figures.
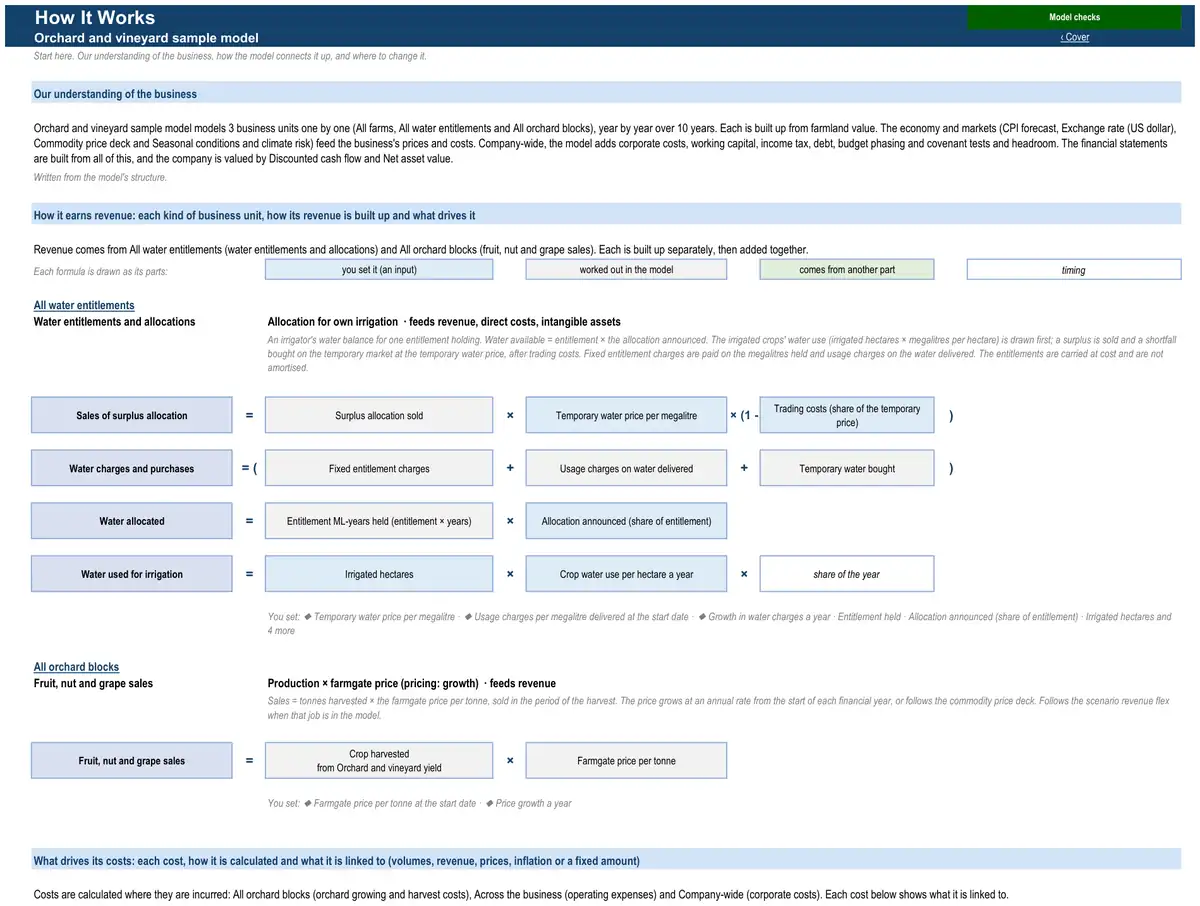
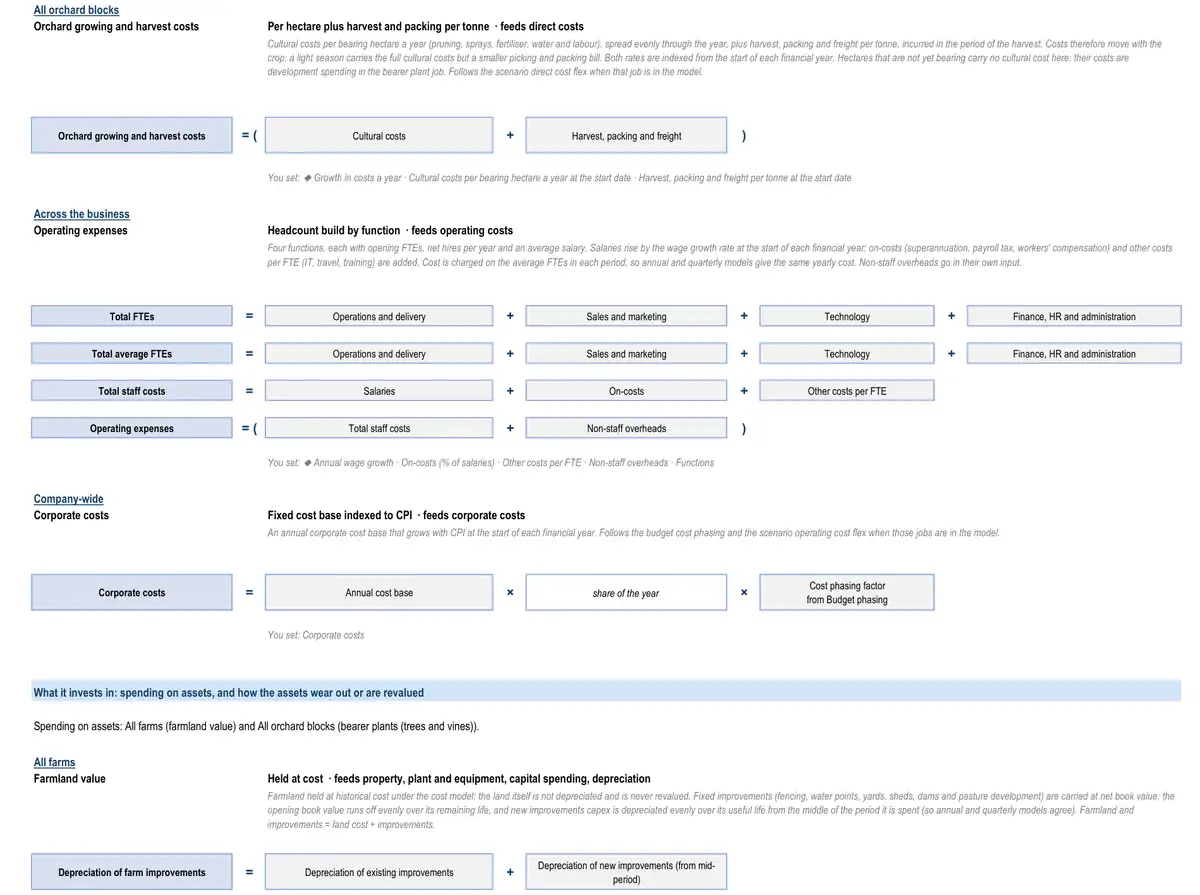
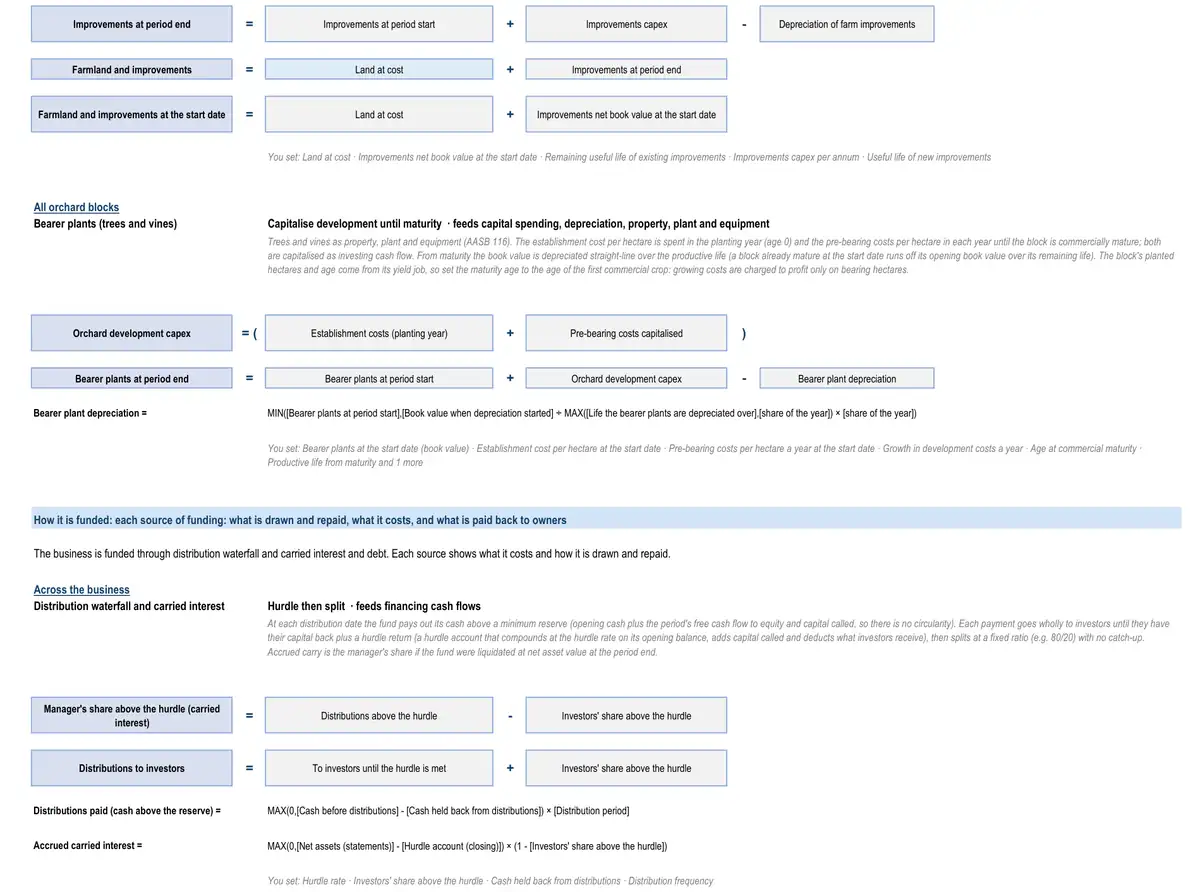
The sample describes no real business. Yours is calibrated to your own figures, so its results are your business’s.
How the model works for an orchard and vineyard.
- How it earns revenue3 formulasWater entitlements and allocations · All water entitlementsSales of surplus allocationSurplus allocation soldTemporary water price per megalitreTrading costs (share of the temporary price)Water entitlements and allocations · All water entitlementsWater charges and purchasesFixed entitlement chargesUsage charges on water deliveredTemporary water boughtWater entitlements and allocations · All water entitlementsWater allocatedEntitlement ML-years held (entitlement × years)Allocation announced (share of entitlement)
- What drives its costs3 formulasOrchard growing and harvest costs · All orchard blocksOrchard growing and harvest costsCultural costsHarvest, packing and freightOperating expenses · Across the businessTotal FTEsOperations and deliverySales and marketingTechnologyFinance, HR and administrationOperating expenses · Across the businessTotal average FTEsOperations and deliverySales and marketingTechnologyFinance, HR and administration
- What it invests in3 formulasFarmland value · All farmsDepreciation of farm improvementsDepreciation of existing improvementsDepreciation of new improvements (from mid-period)Farmland value · All farmsImprovements at period endImprovements at period startImprovements capexDepreciation of farm improvementsFarmland value · All farmsFarmland and improvementsLand at costImprovements at period end
- How it is funded3 formulasDistribution waterfall and carried interest · Across the businessManager's share above the hurdle (carried interest)Distributions above the hurdleInvestors' share above the hurdleDistribution waterfall and carried interest · Across the businessDistributions to investorsTo investors until the hurdle is metInvestors' share above the hurdleDebtRepaymentsScheduled repaymentsPrepayments from an equity raise and the cash sweep
- How profit becomes cash3 formulasWorking capitalTrade receivablesRevenuefrom statementsDebtor daysDays in periodWorking capitalInventoryDirect costs (positive)from statementsInventory daysDays in periodWorking capitalTrade payablesCash operating costs (positive)from statementsCreditor daysDays in period
24 parts, each one tested.
Every part is a tested building block with its own checks: yours is put together from the ones your business needs.
- CPI forecastConsensus curve with long-run anchor
- Exchange rate (US dollar)Exchange rate by financial year
- Operating expensesHeadcount build by function
- Corporate costsFixed cost base indexed to CPI
- Working capitalFull working capital
- Income taxCorporate rate with tax losses
- DebtAmortising term loan
- Discounted cash flow valuationDCF on free cash flow to the firm
- Net asset valueBook net asset value
- Commodity price deckFlat real pricesPrice paths for the farm, fish and forest commodities in the model — grain, oilseeds, cotton, sugar, beef, lamb, pork, wool, milk, fish, logs, fertiliser and feed — that sales and cost methods read as indices.
- Seasonal conditions and climate riskSeason type by yearA season factor that scales yields, carrying capacity, receivals, input demand (or, for ski resorts, snow and skier visits) for drought, average and good years.
- Key-metric summaryLast-twelve-month and run-rate metrics
- Budget phasingSeasonal profile of twelve monthly weights
- Covenant tests and headroomLVR, gearing and ICR for property
- Feasibility metricsCash-flow returns
- Distribution waterfall and carried interestHurdle then split
- Discount rate (WACC)CAPM at target gearing
- Completed valueCapitalised income
- Farmland valueHeld at costValue of farmland and fixed improvements — held at cost, revalued, or at fair value for leased-out farms.
- Water entitlements and allocationsAllocation for own irrigationWater available from each entitlement holding — its allocation, use, trade and charges — and its carrying value.
- Orchard and vineyard yieldYield curve by tree ageBearing hectares and tonnes harvested from each block as trees or vines mature, alternate-bear and age.
- Fruit, nut and grape salesProduction × farmgate priceRevenue from each block's crop — saleable fruit by grade and market × price.
- Orchard growing and harvest costsPer hectare plus harvest and packing per tonneCosts of growing, harvesting and packing each block's crop.
- Bearer plants (trees and vines)Capitalise development until maturityTrees and vines are property, plant and equipment (AASB 116) — development costs are capitalised until commercial production, then depreciated over the productive life.
The numbers it tracks.
- 01tonnes per bearing hectare
- 02packout %
- 03cost per kg
- 04EBITDA per planted hectare
- 05bearer plant value
- 06share of hectares not yet bearing
What it is used for.
- Operating forecastGuide · Financial projections
- Budget and rolling forecastGuide · Cash flow forecast
- ValuationGuide · DCF valuation model
- Lending and credit analysisGuide · Three-statement model
- Development feasibilityGuide · Financial modelling services
- Closed-end fund, syndicate or trust
More in farming, fishing and forestry.
- Broadacre cropping farm financial model
- Beef and sheep farm financial model
- Dairy farm financial model
- Greenhouse grower financial model
- Aquaculture farm financial model
- Cattle feedlot financial model
- Chicken meat producer financial model
- Egg producer financial model
- Pork producer financial model
- Vegetable grower financial model
- Plant nursery and turf grower financial model
- Medicinal cannabis producer financial model
- Fishing company financial model
- Timber plantation financial model
Looking for an orchard and vineyard financial model template? Ours arrives built for your business, with your figures in it.
See a finished model, sheet by sheetThe sample is built on illustrative figures and describes no real business. Models are calculations prepared from the information you provide. They are not financial advice and must be independently verified. See our terms.